
Blogs
Main-Chain Liquid Crystalline Polymer Market: How a 7.42% CAGR Reshapes Strategy Through 2032
By pmarketresearch, 2026-09-18
Main-Chain Liquid Crystalline Polymer Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview and Structural Challenges
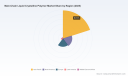
The main-chain liquid crystalline polymer (LCP) market has established itself as a critical enabler for high-performance engineering applications, driven by an unambiguous demand trajectory. Revenue expanded from approximately $1,024 million in 2020 to $1,466 million in 2025, and forward projections indicate sustained momentum toward $2,420 million by 2032. This trajectory translates to a compound annual growth rate of 7.42 percent across the 2026 to 2032 forecast horizon, reflecting a market that is no longer niche but structurally embedded in advanced manufacturing ecosystems. Growth is not evenly distributed across applications or geographies, yet the underlying expansion is anchored by sectors where dimensional stability, thermal resilience, and flow characteristics during precision molding are non-negotiable.
Despite the positive macro trajectory, the industry confronts several structural friction points that will define competitive positioning in the coming years. First, supply chain fragility around specialty monomers creates persistent cost and availability volatility. Purified terephthalic acid and hydroxybenzoate derivatives, which form the backbone of main-chain LCP chemistry, operate within constrained global supply networks. Limited supplier concentration, coupled with batch polymerization requirements, means producers cannot easily decouple from raw material price swings or logistical bottlenecks. This structural premium, often trading at roughly double the cost of high-temperature nylons, limits aggressive substitution in cost-sensitive applications while simultaneously reinforcing the material's value proposition where performance justifies expense.
Second, the regulatory environment is lengthening qualification cycles and raising compliance overhead. Updated chemical safety review frameworks in major markets, alongside evolving disclosure expectations under prevailing chemical strategies, require more extensive testing, traceability documentation, and lifecycle transparency for new LCP grades. These requirements are not peripheral; they directly impact time-to-market for formulation adjustments, additive packages, and biologically balanced variants. For high-volume electronics and mobility customers operating on tight product launch schedules, extended qualification timelines create planning uncertainty and can delay adoption even when technical performance is compelling.
Liquid Crystal Polymers (LCPs) Market
Third, the market is transitioning from performance-driven acceptance to sustainability-conditioned procurement. Original equipment manufacturers and tier suppliers increasingly expect certified green feedstocks, mass-balance traceability, and circular chemistry options alongside thermal and mechanical specifications. This shift does not eliminate demand for conventional main-chain LCPs, but it reshapes purchasing criteria and rewards producers who integrate environmental credentials into product architecture rather than treating them as aftermarket messaging. The convergence of raw material constraints, regulatory elongation, and sustainability-conditioned demand creates a market where scale alone is insufficient. Competitive advantage is migrating toward formulation agility, feedstock diversification, and qualification speed.
Key Drivers Shaping Market Trajectory
Technical Innovation and Formulation Breakthroughs
Material science progress remains the most direct catalyst for expanded LCP adoption. Recent chemistry refinements have focused on balancing high-heat resistance, flame retardancy, and injection flow without sacrificing dimensional tolerances. For high-frequency electronics, 5G infrastructure, and electric vehicle power management, formulators have engineered grades that maintain signal integrity and thermal stability while enabling thinner wall sections and higher component density. The ability to tailor monomer ratios, modify end-group terminations, and integrate specialty additives without disrupting liquid crystalline ordering has extended LCP relevance into applications that previously relied on metal substitution or lower-performance thermoplastics.
A notable example of formulation direction is the introduction of biomass-balanced grades that preserve performance while addressing procurement decarbonization requirements. By applying mass-balance accounting to bio-derived feedstocks, producers have delivered LCP variants that maintain thermal and mechanical characteristics while providing a credible pathway for customers seeking scope reductions in their supply chain emissions. This development signals a broader shift: sustainability is increasingly being engineered into polymer architecture rather than layered on through end-of-life messaging alone.
Policy and Regulatory Environment
Regulatory frameworks are actively reshaping how LCP grades are developed, qualified, and deployed. Chemicals legislation in major jurisdictions continues to tighten testing protocols, disclosure expectations, and substance evaluation timelines. For LCP producers, this means new grades and modified formulations face longer qualification cycles, and customers require more visible documentation around chemical safety, traceability, and compliance status. The operational effect is twofold: it raises barriers to rapid product churn and rewards companies with mature regulatory infrastructure, standardized testing data packages, and established customer qualification relationships.
Simultaneously, policy emphasis on safer chemistries and circular solutions is altering feedstock preferences. Procurement teams increasingly weigh certified feedstocks, mass-balance traceability, and lower-impact sourcing as material selection criteria, particularly in automotive, electronics, and medical supply chains. This environment favors producers that can deliver both performance assurance and verifiable sustainability credentials, while it pressures laggards who must retrofit compliance or feedstock strategy after product architecture decisions are already locked.
Liquid Crystal Polymer (LCP) Films and Laminates Market
Demand-Side Evolution in Key End-Use Markets
Demand is shifting not only in magnitude but in specification. Electrical and electronics applications continue to anchor volume, driven by miniaturization, high-speed data transmission, and thermal management requirements in consumer devices, network infrastructure, and advanced driver-assistance systems. Automotive demand is growing as electrification expands the need for lightweight, heat-resistant, and dimensionally stable components in battery-related assemblies, charging systems, and under-hood modules. Aerospace and defense applications reinforce the market's high-performance core, where strict qualification standards and long service-life expectations reward materials that deliver consistent behavior under extreme thermal and mechanical stress.
Industrial and medical applications add a different growth pattern: lower volume per grade but higher specification precision, especially in semiconductor processing equipment, medical device components, and precision instrumentation. Across these segments, purchasing decisions are becoming more integrated. Procurement, engineering, and sustainability teams increasingly evaluate LCP grades against a combined scorecard of thermal performance, flow behavior, regulatory readiness, and feedstock credentials. The result is a market where multi-attribute value propositions outperform single-dimension price competition.
Supply Chain and Cost Structure Dynamics
Cost structure remains a defining constraint and opportunity. Main-chain LCP pricing carries a structural premium relative to high-temperature nylons because of batch polymerization economics and the reliance on specialty monomers sourced through narrow supply channels. This cost gap limits broad displacement into commoditized applications but protects margins for producers who can deliver differentiated performance, regional supply proximity, and qualification support. Capacity expansions in localized manufacturing footprints are increasingly important for reducing logistics risk, shortening lead times, and improving service levels for high-volume customers who require consistent supply more than marginal unit-cost savings.
The competitive response to cost and supply complexity has been uneven. Leading producers are expanding regional capacity, integrating feedstock strategy into product design, and shortening qualification timelines through standardized data packages. Smaller or less diversified players face the strain of raw material volatility, longer compliance cycles, and customer expectations that increasingly demand more than technical specifications. In this environment, the market's cost structure is not merely a pricing issue; it is a strategic variable that shapes regional supply strategy, customer partnerships, and the pace at which new grades can be commercialized.
Competitive Landscape and Leading Strategies
The main-chain LCP market is characterized by concentrated leadership, with a core group of producers capturing a substantial share of volume and value. The competitive field reflects both legacy formulation expertise and accelerating strategic maneuvering across capacity, acquisition, and sustainability-driven product development. Rather than competing purely on price, leading companies are competing on technical specificity, regional supply assurance, qualification speed, and feedstock strategy.
Among the most prominent participants, Celanese Corporation has positioned its Vectra and Zenite resin and compound portfolio around high-performance electronics, connectors, and automotive applications, emphasizing flow, heat resistance, and dimensional stability. Its recent commissioning of additional LCP production capacity in China reflects a strategic emphasis on local supply for electronics and 5G-related applications, shortening lead times and improving service responsiveness in a region that remains central to electronics demand growth. Polyplastics Co., Ltd. has built its LAPEROS brand around precision molding for semiconductors, medical technology, and automotive applications, and has advanced a biomass-balanced variant using a mass-balance approach with bio-derived raw materials. This move illustrates a broader competitive trend: sustainability is being incorporated as a product attribute rather than a separate communications exercise.
Sumitomo Chemical Co., Ltd. supplies Sumikasuper resins for electronics and high-heat applications, and its acquisition of an additional LCP neat resin business from Syensqo signals a deliberate effort to strengthen offerings in ICT and mobility applications. The transaction highlights a consolidation dynamic in which incumbents are acquiring formulation capability, customer relationships, and product breadth to accelerate positioning in high-growth applications. Toray Industries, Inc. manufactures SIVERAS main-chain LCP materials for electronics and high-frequency applications, with particular emphasis on films and precision components, reinforcing a strategy centered on specialized form factors rather than commodity resin volume. Solvay S.A. through Syensqo provides Xydar grades, including high-heat and flame-retardant variants for EV battery insulation and industrial uses, aligning its portfolio with thermal safety and electrification-driven demand. Ueno Fine Chemicals Industry, Ltd. focuses on main-chain LCP production for high-performance engineering plastics in electronics and other demanding sectors, while Kuraray Co., Ltd. offers main-chain LCP materials including films and fibers for electronics and high-strength applications, extending the material's reach into structural and functional formats beyond conventional molding resins.
The competitive landscape is evolving along several vectors. Consolidation is evident through targeted acquisitions that expand resin portfolios and deepen application coverage, particularly in ICT and mobility. Differentiation is increasingly based on formulation specificity, regulatory readiness, and sustainability-enabled product variants rather than generic performance claims. Regional supply strategy has become a competitive lever, as customers prioritize local or near-local production to mitigate logistics risk and improve responsiveness. At the same time, the market is not closing to new entrants entirely, but entry barriers are rising. Specialty monomer access, batch polymerization know-how, qualification relationships, and sustainability certification infrastructure all raise the threshold for meaningful market participation. The likely trajectory is continued concentration among established producers with diversified application coverage, while niche players survive by serving highly specialized grades or regional demand pockets that larger portfolios do not prioritize. Competitive success will increasingly depend on how effectively companies integrate technical performance with regulatory compliance, feedstock strategy, and localized supply reliability.
PW Consulting Chemical & Energy Research Center
Forward-Looking Trends and Commercial Implications
Over the next three to five years, the main-chain LCP market is likely to follow three interlocking trends that will shape both opportunity and risk. First, demand growth will remain anchored in electrification, advanced electronics, and precision engineering, but the growth will be increasingly grade-specific. General-purpose thermal materials will face substitution pressure, while LCPs engineered for high heat, flame resistance, signal integrity, and precision molding will capture disproportionate value. This means commercial opportunity will concentrate in applications where LCP's structural advantages are difficult to replicate, especially in battery-related assemblies, high-frequency electronics, connector systems, and demanding medical or aerospace components.
Second, sustainability-enabled product architecture will move from differentiator to baseline expectation in premium procurement channels. Biomass-balanced grades, certified feedstocks, and mass-balance traceability will increasingly appear in supplier selection criteria, especially for multinational OEMs and tier suppliers with public decarbonization commitments. Companies that can pair verified sustainability credentials with consistent performance and fast qualification will gain access to a widening premium procurement segment. The risk is that sustainability claims become commoditized if they are not supported by credible mass-balance accounting, transparent disclosure, and robust qualification data.
Third, regional supply strategy and qualification speed will become more decisive in capturing volume. As raw material constraints persist and regulatory review lengthens, customers will favor suppliers that can reduce logistics risk, maintain consistent lot quality, and provide standardized compliance documentation. Capacity expansions in or near key demand regions, paired with efficient qualification support, will help secure long-term supply agreements. The downside risk is that supply expansion without feedstock diversification or regulatory readiness can strand capital in grades that lose competitiveness as customer expectations evolve.
Actionable Recommendations for Decision Makers
For manufacturers and material specifiers, the priority is to align grade selection with application-specific performance thresholds while building sustainability and regulatory readiness into the sourcing decision early. Evaluate LCP grades not only on thermal and flow properties but also on qualification timelines, feedstock credentials, and regional supply reliability. Where electrification, high-frequency electronics, or precision components are involved, prioritize grades with demonstrated performance in relevant thermal, flame, and dimensional stability conditions, and confirm that the supplier can support traceable documentation and accelerated qualification.
For investors and corporate strategists, the market rewards focused exposure to high-value applications and producers with diversified resin portfolios, regional supply footprints, and credible sustainability integration. Monitor consolidation activity, capacity additions, and product launches that deepen positioning in ICT, mobility, and precision medical or aerospace segments. Assess feedstock strategy and regulatory preparedness as leading indicators of commercial resilience, since these factors increasingly determine how quickly new grades can reach customers and how sustainably margins can be defended amid raw material volatility.
For procurement and supply chain leaders, the strategic question is no longer whether LCP delivers performance, but which supplier can deliver performance consistently under evolving compliance and sourcing expectations. Negotiate for data transparency, qualification support, and regional supply assurance alongside unit pricing. Build multi-grade sourcing strategies that balance performance-critical applications with cost-sensitive uses, and ensure that sustainability claims are supported by verifiable mass-balance or feedstock certification rather than generic messaging. Detailed segment-level volume patterns, regional demand distribution, and customized procurement or investment scenarios can sharpen these decisions significantly, and the complete market report provides the granular data needed to translate these strategic insights into concrete sourcing, investment, and product-development actions.
For detailed analysis of this topic, please visit the official page: Main-Chain Liquid Crystalline Polymer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Global Pharmaceutical Grade Taurine Market: 5.24% CAGR Signals Next Growth Phase
By pmarketresearch, 2026-09-18
Strategic Horizons: Navigating Growth and Complexity in the Global Pharmaceutical-Grade Taurine Market
Market Landscape: Sizing the Opportunity, Recognizing the Fault Lines
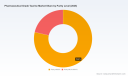
The global pharmaceutical-grade taurine market has entered a phase of measured, structurally reinforced expansion. Between 2020 and 2025, the market value progressed from approximately USD 194.5 million to an estimated USD 245.5 million, reflecting a compound annual growth rate of 5.24 percent over the historical period. Looking ahead to 2032, the trajectory points toward a valuation exceeding USD 351 million, with growth gradually stabilizing as the market matures. This expansion is not merely a reflection of incremental demand; it signals a broader integration of taurine into standardized clinical nutrition protocols, essential ophthalmic formulations, and standardized parenteral support systems. Despite the steady growth profile, the market operates within a tightly structured ecosystem. The top three players command more than two-thirds of global commercial volume, while the leading five entities collectively represent over 84 percent of total revenue generation. Such concentration shapes pricing dynamics, supply reliability, and regulatory responsiveness across downstream buyers. It also creates structural dependencies that become increasingly visible when external shocks emerge. Several critical challenges and turning points define the current operating environment. First, the transition from commodity-grade to pharmaceutical-grade material requires stringent purity thresholds, rigorous impurity controls, and batch-level traceability. Manufacturers face mounting pressure to align chemical synthesis workflows, energy-intensive purification cycles, and documentation practices with increasingly demanding pharmacopeial expectations. Second, raw material and operational cost volatility introduces margin compression risks. Periods of sharp price escalation, driven by feedstock availability, energy expenditures, and logistical bottlenecks, have forced procurement teams and manufacturers to rethink contractual frameworks and inventory buffering strategies. Third, regulatory scrutiny continues to deepen as taurine moves deeper into clinical nutrition, hospital-based formulations, and specialized pediatric applications. Compliance expectations now extend beyond basic certification toward continuous audit readiness, pharmacopeial alignment, and demonstrable supply chain transparency. These overlapping pressures are not merely operational friction points; they represent structural filters that will determine which organizations capture sustainable value in the coming years.
Market Structure and Concentration Dynamics
The geographic and application distribution of demand reveals a market shaped by regional manufacturing ecosystems, clinical practice patterns, and regulatory traditions. Asia Pacific anchors a substantial share of global volume, reflecting integrated production capacity, expanding nutraceutical and pharmaceutical demand, and established export-oriented manufacturing networks. North American and European markets contribute a combined share that underscores mature clinical nutrition frameworks, established ophthalmic product pipelines, and strong pharmacopeial compliance expectations. More emerging demand regions, while currently smaller in absolute scale, are gradually institutionalizing procurement standards that favor documented quality systems over purely cost-driven purchasing. Purity segmentation further clarifies market evolution. High-purity segments exceeding 99.5 percent purity capture the majority of value, a pattern that highlights the premium placed on clinical reliability and regulatory acceptability. Mid-tier purity ranges, while still commercially relevant, increasingly serve applications where formulation requirements or cost structures allow slightly broader specification windows. This bifurcation illustrates how buyers are progressively aligning specification requirements with clinical risk profiles, rather than applying uniform quality thresholds across all use cases.
Core Drivers Reshaping the Market Trajectory
Several interconnected forces are steering the market’s evolution. Understanding these drivers is essential for organizations evaluating capacity expansion, procurement strategy, or partnership positioning.
Technological Innovation and Manufacturing Precision
The shift toward pharmaceutical-grade taurine has elevated the importance of controlled synthesis pathways, purification efficiency, and impurity management. Traditional production relies on chemical synthesis from petrochemical-derived intermediates, followed by multi-stage purification to meet pharmacopeial thresholds. Achieving consistent purity above 99.0 percent requires careful control over energy consumption, reagent quality, crystallization conditions, and analytical verification. Recent operational developments illustrate how manufacturers are responding. Several leading producers have reaffirmed or expanded international quality certifications, reinforcing capabilities that span food, pharmaceutical, and nutraceutical channels. Such certification portfolios do more than satisfy audit requirements; they signal operating discipline that enables participation in regulated supply chains where documentation, traceability, and process consistency carry commercial weight. In parallel, certain international producers have invested in biologically derived or fermentation-based pathways to differentiate in quality perception and sourcing narrative. While synthetic routes remain dominant in terms of volume, alternative production approaches are gaining attention in specialized pediatric and clinical nutrition segments, where source transparency and refinement standards influence procurement decisions. The broader implication is that technology strategy is no longer limited to yield optimization. It now encompasses qualification readiness, batch-to-batch consistency, and alignment with region-specific pharmacopeial expectations.
Regulatory and Compliance Evolution
Regulatory environments continue to shape product specifications, documentation requirements, and market access pathways. Pharmaceutical-grade taurine is expected to align with major pharmacopeial monographs and associated impurity limits, particularly when used as an active pharmaceutical ingredient or functional excipient in hospital formulations, clinical nutrition, and ophthalmic products. Compliance is increasingly understood as a continuous operating state rather than a periodic certification event. Audit readiness, quality management integration, environmental controls, and food-safety-aligned systems have become baseline expectations for suppliers targeting regulated applications. This regulatory tightening is also changing how buyers assess risk. Procurement teams are placing greater emphasis on documented GMP compliance, standardized testing protocols, and transparent chain-of-custody arrangements. In ophthalmic and infant nutrition segments, where clinical stakes are higher and formulation tolerances are narrower, the cost of quality lapses exceeds the cost of prevention by a wide margin. Regulatory alignment therefore functions as both a market entry requirement and a strategic differentiator that supports premium positioning and long-term customer retention.
Demand-Side Shifts Across Clinical and Nutritional Applications
Demand growth is being reinforced by continued use of taurine in established clinical applications, including infant formula, ophthalmic solutions, parenteral nutrition, and selected oral pharmaceutical preparations. In infant nutrition, taurine remains relevant because of its functional role in early development formulations and its historical integration into specialized pediatric nutrition frameworks. In ophthalmology, taurine continues to appear in eye strain relief and supportive eye care formulations, a usage pattern reinforced by recent product introductions that incorporate taurine into pediatric and general eye drop platforms. These product developments illustrate that taurine’s clinical relevance is not static; it is being adapted into contemporary formulation strategies that address consumer expectations, pediatric safety considerations, and supportive care positioning. Parenteral nutrition and oral pharmaceutical use add further demand layers, particularly where standardized amino acid support and metabolic stabilization are required. In these settings, pharmaceutical-grade assurance is a prerequisite, not an optional enhancement. As hospital formularies and clinical nutrition protocols become more standardized across regions, taurine’s inclusion in approved preparation lists and institutional supply specifications creates a recurring demand base that is less sensitive to short-term consumer trends and more dependent on consistent supply performance.
Supply Chain Stress, Cost Volatility, and Strategic Sourcing
Cost volatility remains a defining market theme. Periods of sharp price movement have been linked to raw material constraints, energy-intensive purification demands, and shifting supply-demand balance across regions. A notable surge pattern observed in recent sector assessments underscores how quickly input costs can affect downstream pricing and contracting behavior. For manufacturers, this environment rewards operating flexibility, forward sourcing discipline, and cost transparency. For buyers, it underscores the importance of multi-source strategies, specification-aligned supplier qualification, and contractual structures that balance stability with responsiveness. The concentration of production among a limited set of large-scale manufacturers amplifies these dynamics. While scale and export readiness provide supply reliability advantages, they also create dependency risks. Organizations that rely heavily on single-source relationships may face greater exposure to production disruptions, certification changes, or regional logistics interruptions. As a result, supply chain strategy is shifting from purely cost-based buying toward resilience-based sourcing, where quality documentation, production redundancy, and geographic diversification receive greater weight in supplier selection.
Competitive Landscape: Strategic Positioning and Emerging Shifts
The competitive field is characterized by a mix of large-scale producers, quality-differentiated manufacturers, and region-specific API suppliers. Rather than competing solely on price, leading participants increasingly align their positioning with certification breadth, purity consistency, pharmacopeial compliance, and channel specialization. Several Chinese manufacturers dominate global output and export volumes, building commercial strength through scale, established international certifications, and broad application coverage across pharmaceutical and nutraceutical segments. Their competitive advantage lies in capacity, cost efficiency, and the ability to serve multiple regulated and semi-regulated markets simultaneously. Certification reaffirmation and expansion across quality, environmental, and food-safety standards further reinforce their ability to operate in demanding supply chains. International players introduce differentiation through production approach, sourcing narrative, and quality systems. A New Zealand-based manufacturer has carved out a position around naturally derived taurine, particularly for infant formula and pharmaceutical applications, using source origin and refinement standards as part of its commercial identity. Japanese producers emphasize fermentation-based manufacturing, rigorous testing, and traceability frameworks that support clinical nutrition and pharmaceutical use cases. Indian manufacturers have established presence through pharmacopeial-aligned offerings with defined purity levels, while United States-based suppliers position themselves around GMP-listed API supply and documented regulatory filings. These differing strategic postures illustrate that the market is not converging toward a single business model. Instead, it is fragmenting around distinct value propositions tied to sourcing, compliance narrative, and application focus.
Differentiation Levers and Strategic Positioning
Across the landscape, several differentiation levers consistently shape competitive outcomes. Purity assurance and impurity control remain foundational, with ≥99.5 percent purity attracting premium positioning in higher-risk clinical applications. Certification breadth functions as a commercial enabler, supporting access to multiple regulatory and customer environments. Traceability and quality documentation increasingly determine whether suppliers can participate in hospital procurement, clinical nutrition programs, and specialized ophthalmic supply channels. Geographic and sourcing narratives matter as well, particularly where buyers associate natural origin, fermentation pathways, or region-specific manufacturing standards with reduced perceived risk. These levers are becoming more important as the market matures. Buyers are no longer choosing suppliers based on unit price alone. They are evaluating total qualification cost, supply reliability, regulatory resilience, and alignment with application-specific risk profiles. In this environment, differentiation is less about claiming broad capability and more about demonstrating consistent performance in the segments that matter most to a given customer base.
Evolution Toward Consolidation, Specialization, and Selective Entry
Market concentration suggests further consolidation pressure, particularly as regulatory expectations rise and qualification costs increase. Smaller or less-documented producers may find it harder to access tightly controlled procurement channels unless they secure partnerships, niche application focus, or regional distribution alignment. At the same time, specialization is creating room for targeted entrants that can serve specific clinical or nutraceutical niches with strong documentation and purity consistency. New entrants are therefore more likely to succeed by addressing distinct specification requirements, regional compliance preferences, or sourcing narratives rather than attempting to compete broadly across all applications. This dual dynamic — consolidation among scale players and specialization among targeted suppliers — is likely to define the next phase of competitive evolution. Organizations that can combine operational reliability with clear application focus will be best positioned to capture value without entering an undifferentiated price competition.
Forward Outlook: Three Trends Shaping the Next Three to Five Years
The market’s next stage will be influenced by a combination of quality-driven procurement, formulation evolution, and supply chain restructuring. These trends are interdependent and will shape both opportunity and risk.
Quality, Compliance, and Specification Premiumization
One of the clearest forward signals is the continued premium on high-purity, well-documented material. As pharmacopeial alignment and GMP expectations become more embedded in procurement decisions, buyers will increasingly reward suppliers who can demonstrate consistent purity, impurity control, and traceability. This does not mean lower-tier specifications will disappear, but their commercial role will increasingly be defined by cost structure and application risk tolerance rather than by default purchasing. Suppliers that can reliably meet the highest specification tiers are likely to see stronger retention in regulated channels, while margin opportunities in commodity-adjacent segments will remain sensitive to input cost cycles.
Application Diversification and Formulation Refresh
Demand will likely be reinforced by continued use in infant nutrition, ophthalmic care, parenteral support, and specialized oral formulations, but the distribution of growth will depend on how manufacturers refresh product portfolios and adapt to regional clinical preferences. The recent introduction of taurine-containing eye care products for pediatric use reflects a broader pattern: taurine is not only maintaining its place in established applications but also being incorporated into contemporary formulations that address specific consumer and clinical needs. Over the next few years, suppliers that can provide formulation-ready quality, stable batch consistency, and application-specific documentation will have an advantage in supporting product pipeline development.
Supply Chain Reconfiguration and Resilience-Driven Sourcing
The combination of production concentration, cost volatility, and regulatory sensitivity is likely to encourage more deliberate supply chain redesign. Buyers may diversify sourcing bases, qualify alternate suppliers, and negotiate contracts that account for energy, feedstock, and logistics variability. Manufacturers may invest more heavily in quality infrastructure, certification continuity, and customer-facing traceability systems to reduce qualification friction and strengthen long-term supply relationships. In this environment, resilience will become a commercial asset, and the ability to demonstrate uninterrupted compliance will matter as much as baseline cost competitiveness. Potential risks include continued raw material and energy price fluctuations, regulatory shifts that alter specification expectations, and geopolitical or logistics disruptions affecting export-heavy supply chains. For high-concentration markets, any production interruption among leading suppliers can have disproportionate downstream effects. Organizations should therefore treat volatility not as a temporary anomaly but as a structural condition that requires planning, flexibility, and documented backup options.
Strategic Actions for Decision Makers
For manufacturers and suppliers, the priority is to reinforce differentiation through certification continuity, purity consistency, and application-focused documentation. Investing in quality systems that support audit readiness and pharmacopeial alignment will reduce commercial friction with regulated buyers. Suppliers should also evaluate whether their positioning is broad enough to serve multiple channels or focused enough to defend premium segments where consistency and traceability are valued more than unit cost. For investors, the most relevant signals are concentration patterns, certification momentum, pricing volatility cycles, and application-specific demand resilience. Markets with strong regulatory alignment and recurring institutional demand tend to reward operators with documented quality systems and stable supply performance. Investment evaluation should therefore weigh not only volume orientation but also qualification capability, geographic exposure, and sensitivity to input cost fluctuations. For procurement and sourcing leaders, the strategic imperative is to balance cost efficiency with resilience. Qualifying multiple suppliers, establishing specification-aligned acceptance criteria, and monitoring certification status can reduce exposure to single-source dependency and price shock. Procurement strategy should also account for application risk: higher-stakes clinical or pediatric use cases warrant stronger documentation and stability requirements than lower-risk formulations. Understanding these dynamics at a segment and supplier level is essential for making informed decisions in a concentrated and specification-sensitive market. Detailed segmentation data, regional breakdowns, and company-level competitive signals can sharpen planning and reduce the uncertainty that often accompanies procurement, capacity, or investment decisions in pharmaceutical-grade ingredient markets.
Taurine Market
Worldwide Pharmaceutical Grade L-Carnitine Market
PW Consulting
For detailed analysis of this topic, please visit the official page: Worldwide Pharmaceutical Grade Taurine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Strategic Trends and Commercial Opportunities in the Worldwide Hands-Free Caddie Market
The global hands-free caddie market has entered a phase of accelerated expansion, transforming from a niche accessory into a strategic hardware category at the intersection of mobility automation and sports technology. Valued at approximately $165.15 million in 2020, the segment has grown consistently to reach $292.8 million by 2025. Projections indicate sustained momentum through the forecast horizon, with annual revenue expected to climb past $587 million by 2032. This trajectory reflects a compound annual growth rate of 10.45%, a pace that signals structural adoption rather than cyclical consumer spending. The growth is underpinned by shifting golfer preferences, mature autonomous navigation stacks, and increasing operator willingness to diffuse capital-intensive assets across higher-volume usage scenarios.
Golf GPS Market
Against this backdrop, three critical inflection points shape the current landscape. First, the technology stack is bifurcating between mature remote-control architectures and rapidly advancing autonomous follow systems that rely on sensor fusion and visual guidance. Second, course operators and equipment managers are reevaluating total cost of ownership as hands-free units begin to influence pace-of-play metrics, labor allocation, and customer retention. Third, safety and interoperability expectations are tightening. Think staggering incidents on inclines, and battery and navigation reliability standards that must hold across varied terrain and weather conditions. These pressure points are not merely compliance hurdles; they are becoming core design parameters that separate durable product lines from short-lived feature experiments.
For executives and investors, the implication is clear: the market is large enough to attract serious engineering investment, yet fragmented enough that strategic positioning, reliability engineering, and go-to-market execution will determine which players capture lasting share. Volume leadership in individual consumer adoption continues to anchor baseline demand, while institutional buyers are increasingly evaluating hands-free assets as operational tools rather than premium add-ons. This dual demand structure creates both scale potential and segmentation complexity, requiring product roadmaps that can serve recreational users and fleet operators without compromising either value proposition.
Key Drivers Reshaping the Hands-Free Caddie Market
Technology Innovation and Autonomous Navigation Maturation
The most consequential driver is the rapid maturation of autonomous following technology. Early remote-control carts solved convenience but left the golfer tethered to a handheld interface. Today, sensor-based follow systems combine radio frequency, ultrasound, visual tracking, and increasingly LiDAR or time-of-flight sensing to maintain a stable hands-free walking experience across uneven terrain and moderate slopes. The practical effect is a shift from reactive remote operation to proactive caddie behavior: obstacle detection, terrain adaptation, reverse-follow modes, and gesture-based control are moving from marketing differentiators to baseline expectations. This evolution lowers the cognitive load for the golfer, improves consistency on hilly layouts, and expands the addressable experience beyond flat, predictable courses.
PW Consulting
From a product strategy perspective, the innovation curve is creating clear trade-offs. High-end autonomous stacks increase unit cost and introduce greater software maintenance, calibration, and sensor lifecycle considerations. Meanwhile, simpler remote-control and assisted-walking configurations remain attractive for price-sensitive segments and fleet deployments where simplicity and durability outweigh advanced autonomy. The competitive question is no longer whether hands-free features exist, but how reliably they perform in edge cases: wet conditions, narrow cart paths, dense tree cover, and steep descents where braking and stability become decisive. Manufacturers that solve these real-world reliability issues are gaining a defensible position in a market where reputation for ruggedness directly influences referral velocity and repeat purchase.
Policy, Safety Standards, and Operational Regulation
Regulatory and safety frameworks are increasingly shaping product architecture. Automatic downhill braking and stability controls are now central design requirements to prevent runaway incidents, particularly on courses with significant elevation changes. This is not only a liability issue; it affects insurance considerations for courses, fleet operators, and rental programs that deploy hands-free units at scale. In parallel, broader occupational safety concerns in the golf sector highlight the value of reducing human exposure to hazards on the course. The industry is witnessing a subtle but meaningful shift: hands-free equipment is being evaluated not only for golfer convenience but also as part of a broader risk-reduction and operational efficiency narrative.
For commercial strategy, this creates an opening for brands that can document safety performance with transparent engineering specifications and consistent testing protocols. It also raises the importance of service and assurance. A hands-free caddie is increasingly treated like a light autonomous asset rather than a simple mobility accessory, which means buyers look for durability certifications, clear maintenance pathways, and product documentation that supports fleet deployment. Companies that proactively align product development with these expectations can convert safety requirements into trust capital, particularly in markets where institutional procurement and course operator adoption are gaining momentum.
Demand-Side Shifts in Golfer Behavior and Course Economics
On the demand side, the market is being reshaped by changing expectations around the walking golf experience. A growing segment of golfers seeks ways to preserve the physical and experiential benefits of walking while minimizing burden and improving pace. Hands-free caddies address this by offering assistance without removing the golfer from a mobile, course-immersive experience. This demand is reinforced by a broader interest in lightweight, foldable, and quick-deploy designs that simplify transport, storage, and daily use. At the same time, individual buyers are increasingly sensitive to battery runtime, terrain performance, and multi-mode flexibility, which means product value is judged across an experience arc rather than a single feature.
Institutional demand is following a different but complementary logic. Golf clubs, resort operators, and rental fleets are evaluating hands-free units as tools that can enhance the guest experience while supporting operational flexibility. For high-traffic properties, the ability to offer a walking option that feels modern and supportive can improve perceived quality, widen appeal to fitness-oriented players, and reduce friction in cart allocation during peak periods. However, fleet adoption introduces distinct buying criteria: robustness, serviceability, theft resistance, battery management, and predictable maintenance costs. This divergence means the market is being pulled in two directions at once, by consumer experience demands and by operator economics, and the winners will be those who design for both without forcing a compromise that weakens either segment.
Cost Structure, Battery Systems, and Supply Chain Realities
Cost dynamics remain a foundational driver. Lithium battery systems, lightweight frames, compact actuation, and integrated electronics have improved the value equation for hands-free caddies, but they also tie product economics to component availability, manufacturing consistency, and after-sales support. As demand scales, manufacturers must manage the tension between performance differentiation and cost discipline. A premium autonomous model may win on capability, but margin sustainability depends on BOM control, service parts availability, and the ability to scale without introducing quality variance. Conversely, value-oriented product lines must avoid the trap of under-specifying critical safety and terrain features in pursuit of lower price points, since poor reliability can damage adoption more quickly than a higher sticker price.
Supply chain considerations are increasingly strategic. Product lines that can modularize core components, standardize battery platforms, and reduce assembly complexity are better positioned to manage cost volatility and accelerate refreshes. At the same time, distribution and service networks matter more as the category grows. A hands-free caddie that performs well in demonstrations but lacks local support can lose momentum quickly in mature golf markets. The commercial opportunity is therefore not only in building a better product, but in building a repeatable delivery model that includes warranty handling, battery replacement pathways, and regional support infrastructure.
Competitive Landscape and Leading Strategies
Differentiated Positioning Across the Value Chain
The competitive field shows clear strategic clusters rather than a single race to the top. MGI Golf has emphasized intelligent navigation and autonomous capability, pairing patented gyroscope and AI-based navigation with rugged terrain performance and expanding its innovation pipeline with new launches at major industry gatherings. Its positioning centers on combining hands-free autonomy with the practical durability expected from a mass-market electric caddie brand. Stewart Golf has leaned into premium engineering and stability on hilly courses, using advanced follow technology to reinforce the walking experience and pace-of-play benefits. CaddyTrek has built recognition around robotic follow models that span ultrasound or RF-based tracking and Smart Vision AI with gesture control, emphasizing terrain capability and flexible operating modes. Robera has focused on gesture-based autonomous following with visual guidance, precision ranging technologies for obstacle avoidance, reverse follow, and remote options, distinguishing its product narrative through high-precision hands-free operation.
Beyond these autonomous-oriented players, other leaders have taken different routes. Kangaroo Golf has emphasized remote-control electric caddies with ergonomic interfaces, lithium batteries, autobrake, and quick-fold designs, prioritizing assisted walking performance and usability. Motocaddy has integrated GPS and remote control into its electric lineup, supporting directional control and an enhanced golfer experience. Club Car has signaled interest in fully autonomous hands-free robotic caddies designed to replicate a caddie-like following experience for walking golfers through wireless integration. PowaKaddy has continued to build electric trolley options that combine GPS and remote features for assisted hands-free walking. Alphard Golf has offered remote electric carts and systems that convert push carts into motorized hands-free operation with strong terrain performance. QOD Golf USA has targeted compact remote and electric caddies with stability features for both hands-free and hands-on walking. This diversity shows a market where autonomy, remote control, and hybrid assisted designs all remain commercially relevant, each serving different price points, user expectations, and deployment contexts.
Market Structure, Concentration, and Strategic Drift
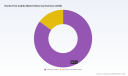
Market concentration provides useful context for competitive strategy. A relatively small group of leading players accounts for a meaningful portion of revenue, with the top three holding around 42.5% and the top five approaching 58.2%. This level of concentration suggests that scale, brand recognition, distribution reach, and product reliability have given established players a structural advantage. At the same time, the share held by the broader field indicates room for specialized entrants, regional differentiation, and technology-led disruption. The market is not yet locked into a winner-take-most pattern, but it is moving toward clearer category leadership in both premium autonomy and value-focused remote-control segments.
The strategic implications are threefold. First, incumbents gain from repeat trust, service ecosystems, and course-level relationships that reduce buyer risk in fleet adoption. Second, specialized players can compete by owning a niche with exceptional execution, whether that means superior hill stability, richer sensor-based autonomy, lighter weight, or better ergonomics. Third, new entrants and adjacent brands can gain traction by bridging gaps between consumer convenience and operator practicality, especially where current offerings are either too premium or too utilitarian for a growing middle segment. The likely evolution is a combination of consolidation among complementary assets and continued fragmentation in feature sets, as brands differentiate around autonomy level, terrain capability, design language, and service economics rather than competing on a single dimension.
Future Trends and Commercial Implications
Over the next three to five years, the hands-free caddie market is likely to be shaped by three interconnected trends. The first is deeper autonomy with more robust perception. Follow systems will continue to integrate visual and ranging sensors, improving consistency in cluttered environments and on challenging terrain. This will raise customer expectations for hands-free behavior and push the category closer to light robotics in terms of reliability, calibration, and user interaction design. Commercially, this favors manufacturers that can pair advanced sensing with practical safety engineering, because the value of autonomy is only realized when it works predictably in real course conditions.
The second trend is broader institutional diffusion. As course operators and rental businesses gain more experience with hands-free units, adoption will increasingly be driven by operational considerations: guest experience, labor optimization, equipment utilization, and service predictability. That shift expands the addressable market beyond individual golfers and encourages product designs that support fleet management, battery logistics, and consistent handling across multiple units. The opportunity lies in offering platforms that can be configured for both retail and institutional use without fragmenting the supply base or sacrificing reliability.
Hand Trucks Market
The third trend is tighter integration with the broader golf technology ecosystem. GPS integration, connectivity features, and software-driven modes will become more common, enabling richer user experiences and better usage visibility for operators. This creates opportunities for services around data-informed maintenance, usage analytics, and upgrades, but it also introduces dependency on software lifecycle management and interoperability. The uncertainty here is not whether connectivity will expand, but whether manufacturers can sustain software support, manage cybersecurity expectations, and avoid fragmented ecosystems that frustrate buyers. Companies that treat the hands-free caddie as a connected mobility product rather than a static accessory will be better positioned to capture recurring value, provided they can deliver dependable support over time.
Actionable Guidance for Decision-Makers
For Manufacturers and Product Leaders
Prioritize reliability where it affects trust most: braking and stability on inclines, terrain adaptability, battery consistency, and intuitive mode switching. Differentiate through engineering substance rather than feature claims alone. Build modular architectures that allow cost control while preserving the ability to introduce advanced autonomous capabilities selectively. Equally important, invest in regional service capacity and parts availability, because post-purchase support increasingly determines long-term reputation in a category where hands-free performance must be proven over repeated use.
For Investors and Strategic Allocators
Focus on companies that combine defensible product differentiation with scalable distribution and clear service economics. The strongest opportunities are likely to emerge where autonomy, durability, and operational support intersect, especially in firms that can address both consumer and institutional demand without forcing an either-or strategy. Assess whether product roadmaps are aligned with sensor maturation, safety expectations, and fleet-ready design, since these factors will shape margin resilience and competitive durability as the market expands.
For Procurement Teams and Course Operators
Evaluate hands-free caddies as operational assets, not just consumer conveniences. Weight total cost of ownership, terrain performance, service response, and battery management alongside user experience. Pilot deployments should test real-course scenarios, not only showroom demonstrations, with particular attention to slope handling, obstacle response, and maintenance turnaround. A disciplined procurement approach reduces downtime risk and improves the likelihood of consistent guest satisfaction.
The market trajectory points to continued growth, but durable advantage will come from execution discipline: safety-led engineering, practical autonomy, cost-aware product design, and support infrastructure that matches commercial ambition. For decision-makers seeking segment-level sizing, regional breakdowns, pricing dynamics, and customized strategy scenarios, the full research report provides the detailed data and scenario analysis needed to translate these trends into precise operating plans.
For detailed analysis of this topic, please visit the official page: Worldwide Hands-Free Caddie Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Zhi Mu Extract Market: 6.74% CAGR Transforming Asia Pacific Growth
By pmarketresearch, 2026-09-18
Strategic Trends and Commercial Opportunities in the Global Zhi Mu Extract Market
Market Overview and Critical Challenges
The global market for Zhi Mu extract, derived from the rhizome of Anemarrhena asphodeloides , has demonstrated steady growth over the past five years, expanding from approximately 37.85 million USD in 2020 to an estimated 52.48 million USD in 2025. Looking ahead, the market is projected to continue its upward trajectory, reaching roughly 82.86 million USD by 2032. This expansion translates to a compound annual growth rate of 6.74 percent between 2026 and 2032, signaling sustained commercial momentum across multiple downstream sectors.
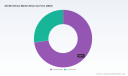
Geographically, the Asia Pacific region accounts for the largest share of total market activity, reflecting both Deep-rooted traditional usage patterns and growing domestic demand for standardized botanical ingredients. North America and Europe represent substantial secondary markets, driven largely by the incorporation of herbal extracts into dietary supplements, personal care formulations, and functional foods. Latin America and the Middle East and Africa collectively represent a smaller but gradually expanding footprint as awareness of botanical ingredients broadens across emerging consumer bases. In terms of physical form, powder extracts command the majority of market activity, while liquid extracts maintain a meaningful but secondary position. Application-wise, cosmetics and personal care represent the largest end-use segment, followed by pharmaceuticals and nutraceuticals, with food and beverages accounting for a more modest share of total demand.
PW Consulting
Despite this favorable growth trajectory, the industry is navigating several structural challenges that will define competitive outcomes over the next decade. First, supply chain concentration and raw material sourcing remain critical vulnerabilities. The primary botanical source for Zhi Mu is cultivated under controlled conditions in China, where extraction processes involve cleaning, drying, and specialized isolation techniques to capture active compounds such as timosaponins. Any disruption in cultivation cycles, quality variability across harvests, or shifts in agricultural input costs can quickly cascade through downstream pricing and availability.
Second, regulatory divergence across key markets is creating compliance complexity for manufacturers and buyers alike. In the United States, herbal products including Zhi Mu extracts are regulated as dietary supplements under DSHEA 1994, which mandates testing for pesticides, heavy metals, and microbial contamination but does not require full pharmaceutical-grade good manufacturing practices. This framework provides operational flexibility but also introduces quality assurance variability that sophisticated buyers increasingly scrutinize. Meanwhile, import dynamics have intensified cost pressures. As of April 2025, US tariffs on China-sourced botanicals reached a minimum rate of 145 percent, significantly altering the cost structure for herbal ingredients entering one of the largest consumer markets globally. This policy shift is forcing supply chain actors to reconsider sourcing strategies, formulation economics, and margin expectations.
Third, market fragmentation presents both a challenge and an opportunity. The competitive landscape remains relatively dispersed, with no single entity commanding dominant market share. This dispersion creates price competition, inconsistent quality standards across smaller producers, and limited brand differentiation in commoditized segments. Companies that can institutionalize quality control, traceability, and application-specific formulation expertise will be best positioned to capture premium positioning as buyers move beyond basic ingredient procurement toward partnership-driven supply models.
Worldwide Picrorhiza Extract Market
Key Drivers Shaping Market Trajectory
Several interlocking forces are accelerating structural change within the Zhi Mu extract market. Understanding these drivers is essential for anticipating where value will concentrate and which capabilities will separate outperforming players from the rest of the field.
Technological innovation and extraction methodology advancement represent the first major driver. The isolation of active botanical compounds, particularly timosaponins, requires precise processing to maintain potency, consistency, and stability across batches. Producers that have invested in standardized extraction protocols, controlled drying stages, and purification methods are better equipped to deliver repeatable specifications demanded by pharmaceutical, nutraceutical, and cosmetic formulators. The ability to offer extracts at defined concentration ratios, maintain low variability in active marker compounds, and document process controls has become a baseline expectation rather than a differentiator. Over time, technological maturity in extraction efficiency will also influence cost structures, enabling producers to manage input volatility while preserving margin integrity.
Policy and regulatory evolution forms the second driver, with direct implications for market access and operating costs. The US tariff environment for China-sourced botanicals has introduced a sharp cost adjustment for importers reliant on Zhi Mu materials. In response, market participants are evaluating diversified sourcing arrangements, inventory planning adjustments, and formulation cost rebalancing. Simultaneously, the regulatory framework governing herbal supplements continues to shape buyer expectations around testing, documentation, and quality assurance. While the current supplement pathway does not mandate pharmaceutical GMP, large buyers in cosmetics and nutraceuticals increasingly impose their own supplier qualification standards that exceed minimum regulatory thresholds. This dynamic rewards manufacturers with robust certification portfolios and documented process controls.
Demand-side shifts in consumer and corporate behavior constitute the third driver. Interest in botanical ingredients continues to grow across personal care, wellness, and functional nutrition categories. Consumers are increasingly attentive to ingredient provenance, clean-label positioning, and transparent sourcing narratives. For Zhi Mu specifically, its traditional usage background and expanding application in modern formulations create a bridge between heritage appeal and contemporary product development. On the corporate side, formulators are seeking botanical ingredients that can be integrated into stable, scalable production processes without compromising product claims or sensory profiles. This has elevated the importance of technical support, specification reliability, and application guidance from ingredient suppliers.
Supply chain and cost structure dynamics represent the fourth driver. Raw material cultivation, extraction processing, certification maintenance, and logistics all influence total delivered cost. As tariff pressures and input variability affect landed costs, companies are reweighting the importance of supply resilience. This includes evaluating supplier geographic concentration, understanding seasonal raw material availability, and assessing the financial impact of certification requirements such as HACCP, ISO22000, ISO9001, BRC, and organic certifications. Producers that can combine cost discipline with verifiable quality credentials are gaining negotiating leverage with downstream buyers who face their own margin and compliance pressures.
Recent commercial activity illustrates how these drivers are already playing out. Several manufacturers have increased visibility at international trade platforms, showcasing botanical ingredients to procurement teams and product developers in Europe and North America. At the same time, certain US-based producers have continued to emphasize organic-certified powder and liquid formats aimed at clean-label applications, reflecting the market's shift toward transparency and specification clarity. These developments suggest that competitive advantage is increasingly tied to market access strategy, certification depth, and the ability to serve application-specific buyer needs rather than price alone.
Competitive Landscape and Leading Strategies
The competitive environment in the Zhi Mu extract market is characterized by a mix of established botanical ingredient manufacturers, specialized extract producers, and regional suppliers with distinct strategic postures. No single company currently dominates the market, which keeps competition dynamic and creates room for differentiation through quality, certifications, and application focus.
Chinese-based manufacturers form the backbone of global supply, reflecting the concentration of raw material cultivation and extraction infrastructure in the region. Several producers have built profiles around standardized herbal extracts for global distribution, backed by certifications such as HACCP, ISO22000, and ISO9001. These credentials support export-oriented business models by signaling process reliability to international buyers. Other manufacturers emphasize customized botanical extracts tailored for human health applications, positioning themselves as flexible suppliers capable of serving bulk demand across pharmaceutical and nutraceutical channels.
A subset of producers is differentiating through organic and sustainable production emphasis. These companies pursue certifications such as BRC, organic approvals, and ISO9001 to serve buyers in pharmaceutical, nutraceutical, and cosmetic applications where ingredient integrity and documentation are especially valued. This orientation aligns with growing buyer interest in traceability and environmentally conscious sourcing narratives. Another group of manufacturers specializes in defined extract ratios for pharmaceutical-focused applications, leveraging long operating histories in botanical extracts and natural ingredients to serve formulators that require consistent specification ranges.
Outside China, US-based production represents a strategically distinct segment. One Honolulu-based manufacturer has maintained a focus on alcohol-free and alcohol-based liquid extracts and tinctures produced in small batches under GMP standards within an FDA-registered facility. This positioning appeals to buyers seeking domestically manufactured options, smaller lot flexibility, and formulation formats suited to tincture and liquid-based product development. Such offerings also respond indirectly to import cost and sourcing risk concerns by providing an alternative supply path, albeit at a different cost profile and scale.
Regional specialists also play important roles. Some suppliers concentrate on natural medical herbs and rhizoma Anemarrhenae for traditional Chinese medicine applications, servicing demand that remains closely tied to heritage usage and specific formulation traditions. Others focus on high-purity extract lines for pharmaceutical and nutraceutical applications, emphasizing product specificity and application-targeted production. The presence of multiple specialized players indicates a market that is not yet fully consolidated and where niche expertise can command meaningful buyer interest.
Leading companies are pursuing differentiation along several axes. One is certification and quality documentation. Manufacturers with multiple recognized certifications are better positioned to pass supplier qualification processes and enter regulated or semi-regulated supply chains. Another axis is application breadth. Companies that can support cosmetics, personal care, pharmaceutical, nutraceutical, and food and beverage buyers with appropriate extract formats and technical support gain cross-market optionality and reduce dependence on a single demand cycle. A third axis is market access and visibility. Participation in major trade shows and regional industry events allows producers to engage directly with international procurement teams, showcase specification capabilities, and gather market feedback that informs product and certification strategy.
The market structure appears likely to evolve through a combination of consolidation, specialization, and new entry. Consolidation may accelerate as larger botanical ingredient groups seek to secure reliable supply, expand certification portfolios, and reduce supplier fragmentation in their own value chains. Specialization will continue to reward producers that commit to specific extract formats, purity thresholds, or application segments. New entrants may emerge where import cost dynamics, domestic manufacturing incentives, or certification advantages create viable niches. Overall, the strategic imperative is moving from volume-based competition toward capability-based competition, where quality consistency, documentation depth, and buyer-facing technical support determine commercial outcomes.
Future Trends and Risk Outlook
Over the next three to five years, several trends are likely to shape how value is created and captured in the Zhi Mu extract market. The first trend is the elevation of specification and traceability as commercial defaults. As downstream buyers in cosmetics, nutraceuticals, and functional foods face greater scrutiny from retailers, regulators, and consumers, ingredient suppliers will be expected to provide more granular documentation, batch-to-batch consistency, and clearer sourcing narratives. This will reward manufacturers that invest in process control and transparent quality systems, while pressuring those that compete primarily on price without supporting documentation.
The second trend is supply chain reconfiguration in response to cost and access pressures. The current tariff environment for China-sourced botanicals is already prompting buyers to reexamine sourcing mix, inventory timing, and formulation economics. While China will likely remain a central source of raw material supply for the foreseeable future, market participants may pursue diversified sourcing strategies, regional manufacturing options, or reformulated product economics to manage cost volatility. This trend creates opportunities for producers with strong certifications, stable supply continuity, and flexible export capabilities, but it also raises the importance of risk planning for buyers dependent on single-source procurement.
The third trend is application expansion beyond traditional use cases. While cosmetics and personal care currently represent the largest demand segment, interest in nutraceuticals, functional food and beverage formats, and specialized liquid extract applications continues to broaden the commercial canvas. Companies that can translate raw botanical material into application-ready ingredients with appropriate stability, sensory compatibility, and claim-supportable specifications will be best positioned to capture growth across these emerging demand pockets.
Worldwide Houttuynia Extract Market
Potential risks and uncertainties should not be overlooked. Regulatory requirements may tighten in key markets, changing testing expectations or documentation thresholds and increasing compliance costs. Trade policy volatility could continue to affect landed costs and disrupt established procurement patterns. Raw material supply remains exposed to agricultural variability, climate influences, and cultivation scale limitations, which could affect availability and pricing at times. Finally, quality inconsistency across smaller producers may trigger buyer consolidation toward fewer, more credible suppliers, intensifying competitive pressure on manufacturers without differentiated credentials or technical capabilities.
Strategic Recommendations for Decision Makers
For manufacturers and ingredient producers, the priority is to strengthen specification reliability, certification depth, and application-specific support. Investing in process controls, documentation, and recognized quality credentials will improve access to downstream buyers with stricter supplier qualification standards. At the same time, producers should evaluate how supply chain risks, including raw material variability and import cost pressures, can be mitigated through capacity planning, diversified customer exposure, and clear positioning around extract formats and application fit.
For investors, the market signals a preference for capabilities rather than scale alone. Opportunity areas include producers with credible certification portfolios, stable quality systems, and demonstrated access to international buyer channels. Sector oversight should also weigh exposure to trade policy shifts, raw material sourcing concentration, and the pace at which demand expands beyond the largest application segments. A disciplined view of margin sustainability under different sourcing and tariff scenarios will help distinguish resilient business models from those vulnerable to cost shocks.
For procurement teams and formulators, the actionable focus is to treat ingredient selection as a multi-dimensional decision rather than a unit-price exercise. Evaluating supplier quality systems, extract format suitability, batch consistency, and documentation readiness can reduce downstream reformulation risk and improve product launch reliability. Diversifying sourcing where feasible and maintaining visibility into supply continuity will also help manage exposure to cost volatility and policy changes.
Keeping pace with specification evolution, certification expectations, and shifting sourcing economics requires timely, granular intelligence. Decision makers who want detailed segmentation data, competitive benchmarking, and customized strategic guidance will find additional value in the complete research report, which extends the analysis with deeper segmentation breakdowns and application-specific commercial implications.
For detailed analysis of this topic, please visit the official page: Worldwide Zhi Mu Extract Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Special Category Semi-trailer Market: Why 5.48% CAGR Changes Everything
By pmarketresearch, 2026-09-18
Strategic Shifts and Commercial Opportunities in the Worldwide Special Category Semi-trailer Market
The worldwide special category semi-trailer market has entered a phase of structural expansion, driven by the need to move oversized, temperature-sensitive, and hazardous cargo across increasingly complex supply chains. Valued at approximately USD 20.96 billion in 2025, the market has grown consistently from a base of roughly USD 16.5 billion in 2020, reflecting a compound annual growth rate of 5.48 percent through 2032. By the end of the forecast period, revenue is projected to approach USD 30.45 billion, signaling durable demand rather than a cyclical upturn. This trajectory underscores a fundamental shift in how heavy and specialized freight is mobilized globally, with manufacturers and fleet operators alike recalibrating capacity, materials, and product architecture to meet evolving operational realities.
Behind the headline growth figures lies a landscape defined by uneven regional momentum and product-level divergence. North America, Europe, and Asia Pacific collectively anchor the largest revenue pools, each shaped by distinct infrastructure maturity, regulatory intensity, and industrial demand profiles. Product categories spanning lowboy, refrigerated, tanker, car carrier, and logging configurations continue to coexist, but their growth trajectories are increasingly decoupled. The market is not growing uniformly; instead, it is being reshaped by application-specific requirements, where logistics and transportation, construction and infrastructure, oil and gas, and food and beverage sectors each impose different payload, durability, and compliance expectations.
Several critical challenges and inflection points define the current market environment. First, the industry is navigating a tightening regulatory perimeter around emissions and safety standards, forcing manufacturers to reconsider powertrain-adjacent design choices and component selection even for non-propelled trailer assets. Second, raw material economics have become a persistent source of margin pressure and strategic trade-offs, as producers balance weight reduction benefits against cost premiums and embedded carbon considerations. Third, the market is experiencing a gradual bifurcation between standardized volume production and highly customized special-category solutions, creating operational complexity for OEMs that must serve both segments without diluting expertise or scale advantages. These dynamics are not temporary friction points; they are reshaping competitive positioning and investment priorities across the value chain.
Core Drivers Reshaping Market Trajectory
Technological innovation is moving beyond incremental improvements and beginning to redefine what special category semi-trailers can deliver in terms of payload efficiency, safety, and operational visibility. Advancements in high-strength steel alloys and engineered aluminum formulations are enabling lighter yet structurally robust configurations, allowing operators to maximize legal payloads without compromising durability. At the same time, integration of telematics, load-sensing systems, and modular coupling architectures is transforming trailers from passive cargo carriers into data-enabled components of smarter freight networks. These capabilities are particularly valuable in special category applications, where load stability, route constraints, and configuration flexibility directly influence utilization rates and total cost of ownership.
The regulatory environment is exerting a parallel and equally powerful influence. Environmental mandates targeting heavy-duty transport are increasingly extending their reach into trailer design and material choices, even when the trailer itself does not generate propulsion emissions. Standards governing braking performance, lighting, structural integrity, and safe operation continue to raise the baseline for market entry, while emissions-related frameworks are nudging manufacturers toward materials and designs that support broader fleet efficiency goals. Compliance is no longer a checkbox exercise; it is becoming a design constraint that rewards early adopters of lighter, more efficient, and easier-to-integrate special category platforms.
PW Consulting
Demand-side behavior is shifting as freight networks prioritize reliability, speed, and cargo integrity across longer and more fragmented routes. Logistics and transportation operators are expanding their reliance on specialized equipment to handle complex multimodal movements, while construction and infrastructure activity is sustaining demand for heavy-lift and low-clearance configurations. Simultaneously, temperature-sensitive and high-value cargo flows are reinforcing the role of refrigerated and secure carrier formats. Buyers are increasingly evaluating trailers not just on acquisition cost but on lifecycle performance, downtime risk, and compatibility with evolving fleet management practices. This evaluation shift is pushing manufacturers to articulate value through durability, configurability, and service support rather than price alone.
Specialty Tire Market
Supply chain and cost structure dynamics complete the driver set. Material availability, energy costs, and production localization decisions are reshaping manufacturing economics, particularly for high-specification special category units that require specialized fabrication and quality control. The relative cost of aluminum versus steel remains a recurring strategic consideration, with aluminum offering measurable weight and payload advantages while carrying a higher upfront price and a materially larger carbon footprint per kilogram produced. In parallel, regional production footprints are being revisited as OEMs seek to reduce lead times, respond to local compliance requirements, and better serve fragmented demand pockets. These supply-side pressures are encouraging more modular design approaches, selective material substitution, and closer alignment between manufacturing capacity and end-market demand clusters.
Competitive Landscape and Leading Strategies
The competitive field in the special category semi-trailer market is defined by a mix of large-scale multinational OEMs and specialized manufacturers with deep application expertise. Companies such as CIMC Vehicles, Schmitz Cargobull AG, Krone Commercial Vehicle Group, Wabash National Corporation, Great Dane LLC, Hyundai Translead, and Kässbohrer occupy prominent positions by combining broad product portfolios with regional manufacturing strength and established aftermarket support. Their scale enables them to serve high-volume logistics segments while maintaining dedicated lines for heavy haul, temperature-controlled, and custom configurations. At the same time, a second tier of specialist producers—including Miller Industries, Cottrell, Faymonville/MAX Trailer, Nooteboom Trailers, Goldhofer, Landoll, Boydstun, and Heil Trailer International—competes on niche proficiency, often winning demand in vehicle transport, car hauling, extendible lowbed, and liquid or dry bulk applications where engineering specificity and operational familiarity carry outsized weight.
Leading players are differentiating through a combination of product breadth, regional responsiveness, and capability depth rather than through price competition alone. Global-scale OEMs lean on standardized platforms, broad service networks, and the ability to offer multiple special category variants from shared manufacturing logic, which helps manage cost while preserving configuration flexibility. Specialist manufacturers, by contrast, often compete by tailoring structural layouts, axle arrangements, and coupling systems to very specific load profiles and route conditions. This dual structure creates a market where scale and specialization coexist, and where the most resilient brands are those that can move between volume-oriented production and highly engineered custom builds without losing quality control or delivery predictability.
Recent market developments point to a landscape that is becoming more transparent, more regionally nuanced, and more responsive to near-term demand signals. Global OEM rankings based on confirmed production output have drawn sharper attention to relative scale and capacity utilization, giving buyers and investors a clearer reference point for manufacturing leadership. At the same time, regional manufacturers are reinforcing their positioning by emphasizing durability, compliance, and service availability for both domestic and export markets. New model-year listings for specialized variants, including paver and heavy-duty configurations, indicate that product refresh cycles and application-specific availability remain key tools for capturing demand in segmented verticals. These signals suggest that competitive advantage is increasingly tied to the ability to align production readiness with localized demand timing.
The market structure is evolving along two intersecting paths: consolidation at the scale end and persistent fragmentation at the specialist end. Larger groups are well placed to absorb compliance costs, invest in material and design innovation, and expand service coverage across regions, which can pressure smaller competitors that lack capital flexibility or geographic reach. Yet the long tail of specialized demand continues to support smaller, highly focused manufacturers that can iterate quickly on custom configurations and build deep relationships in narrow application segments. New entrants are most likely to succeed where they can combine a clear application focus with reliable compliance, cost-competitive material strategies, and credible after-sales support. For incumbents, the strategic question is not whether to pursue scale or specialization, but how to organize both within a single operating model that can switch efficiently between standardized output and custom engineering.
Forward Outlook: Trends Shaping the Next Three to Five Years
One of the most consequential trends ahead is the continued integration of material and design innovation with regulatory and efficiency pressures. As emissions-related standards for heavy-duty transport tighten and fleet operators look for every available lever to improve utilization and reduce operating cost, lighter and more structurally efficient special category trailers will gain preference in many applications. Expect greater experimentation with mixed-material architectures, higher-strength steel grades, and selective aluminum use where payload or fuel-efficiency gains justify the cost premium. The commercial opportunity lies in offering modular, application-tuned platforms that let buyers balance weight, durability, and total cost of ownership without committing to a single material philosophy across the entire fleet.
Semitrailer (Semi-Trailer) Market
A second trend is the growing importance of configuration agility and regional production alignment. Demand for special category equipment is unlikely to homogenize; instead, it will continue to cluster around specific industrial corridors, resource projects, and logistics hubs. Manufacturers that can tailor axle layouts, deck heights, tank formats, and carrier adaptations to local requirements—while maintaining repeatable quality and reasonable lead times—will capture disproportionate share in high-value segments. This creates an opening for producers that invest in flexible fabrication, regional service presence, and rapid customization workflows, especially in markets where infrastructure projects, energy activity, or temperature-controlled freight are expanding faster than the broader fleet base.
A third trend is the gradual shift from equipment purchase decisions to lifecycle and compliance-aware procurement. Buyers are increasingly weighing safety standards, emissions-linked material implications, maintenance access, and integration with fleet data systems when selecting special category semi-trailers. This creates room for manufacturers and suppliers that can demonstrate transparent performance characteristics, predictable service intervals, and compatibility with broader operational management tools. The associated risk is that misalignment between product design and future compliance expectations could erode competitiveness, particularly if standards converge in ways that favor lighter, more efficient, and more easily certified configurations. Uncertainty around material costs, regional demand pacing, and the exact timing of regulatory effects will require scenario-based planning rather than fixed long-term commitments.
Actionable Priorities for Decision-Makers
For manufacturers, the immediate priority is to strengthen the balance between scale efficiency and application-specific engineering. That means investing in modular platforms, clarifying material strategies in light of both cost and carbon considerations, and building production flexibility that can absorb regional demand swings without sacrificing delivery reliability. Firms that can demonstrate credible compliance readiness, predictable customization lead times, and strong service coverage will be better positioned to defend margins as competition intensifies around differentiated capability rather than base pricing.
For investors, the most relevant signal is that growth is concentrated in specific product and application pockets rather than distributed evenly across the market. Capital allocation should favor producers with clear positioning in high-demand special categories, durable regional manufacturing footprints, and the operational discipline to manage material cost volatility. Diversification into adjacent service, aftermarket, and configuration-support capabilities can also provide resilience when new equipment cycles slow or when procurement shifts toward lifecycle value.
For procurement teams and fleet operators, the strategic imperative is to evaluate special category semi-trailers as long-term operational assets rather than short-term cost items. Decisions should incorporate payload efficiency, compliance trajectory, material trade-offs, and service accessibility alongside acquisition price, with particular attention to how equipment choices align with anticipated cargo mix and route complexity. Given the pace of regulatory, material, and demand-side change, access to granular segmentation data and scenario-based market intelligence is increasingly valuable for reducing procurement risk and timing capacity decisions more effectively. For organizations seeking a deeper dive into segment-level dynamics, regional comparisons, and tailored strategic implications, the full research report provides the detailed breakdown needed to translate these trends into operational and investment decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Special Category Semi-trailer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Enalapril Market CAGR Insights: What the 2032 Growth Path Means
By pmarketresearch, 2026-09-18
Strategic Trends and Commercial Opportunities in the Worldwide Enalapril Market
Market Overview and Core Challenges
The global enalapril market has demonstrated steady expansion over the past half-decade, reflecting the persistent demand for effective cardiovascular therapeutics. From 2020 to 2025, the market evolved from a base of approximately 538 million USD to an estimated 649 million USD in the current year, indicating a compound annual growth rate of 3.82 percent through the forecast horizon extending to 2032. This trajectory suggests that while the molecule is well-established, the addressable market continues to expand alongside broader epidemiological shifts and healthcare accessibility improvements. The growth pattern, however, is not linear, with projected fluctuations in the late 2020s highlighting the sensitivity of revenue streams to regulatory approvals, generic erosion, and regional pricing pressures.
Despite this foundational stability, the industry is navigating several structural challenges that threaten to reshape competitive dynamics. First, the maturation of generic penetration has intensified price competition, compressing margins for formulators who lack differentiated supply chain capabilities or regulatory agility. With the market characterized by moderate concentration, where the top three firms capture roughly 38 percent of revenue and the top five account for over half, smaller players must rely on niche capabilities or regional partnerships to maintain relevance. Second, supply chain fragility remains a persistent risk, particularly given the heavy reliance on imported active pharmaceutical ingredients for cardiovascular therapies in major consumption markets. This dependency exposes manufacturers to geopolitical disruptions, regulatory audits, and cost volatility that can ripple through finished product pricing. Third, reimbursement scrutiny and formulary management in developed healthcare systems are increasingly favoring cost-optimized procurement, forcing suppliers to demonstrate value beyond molecule efficacy alone. These intersecting pressures create a pivotal moment where operational efficiency, regulatory foresight, and market access strategy determine long-term positioning.
Key Drivers of Market Evolution
Technological and manufacturing innovation continues to influence how enalapril is produced, formulated, and delivered. Advances in process chemistry and continuous manufacturing principles have enabled more consistent API quality and reduced batch variability, which is especially relevant for narrowly therapeutic molecules where impurities or potency drift can trigger regulatory action. A practical illustration of shifting formulation priorities emerged in early 2024, when a major generic manufacturer received FDA clearance for an enalapril maleate oral solution. This approval expanded the available dosage forms beyond conventional tablets, addressing patient populations with swallowing difficulties or pediatric needs and signaling that incremental formulation innovation remains a viable pathway to differentiation even in a mature generic landscape.
Regulatory and policy frameworks are simultaneously reshaping market access and competitive entry. The authorization landscape has shown renewed openness to specialized indications, as evidenced by a 2023 European Medicines Agency decision clearing a pediatric heart failure indication for an enalapril-based product. Such regulatory milestones matter because they extend the clinical utility of the molecule into underserved patient groups, create labeling distinctions that can support market segmentation, and encourage manufacturers to invest in targeted clinical or regulatory submissions rather than competing solely on bulk generic volume. At the same time, regulatory scrutiny on supply chain integrity continues to tighten, reinforcing the importance of documented quality systems and traceability for both API producers and finished dosage manufacturers.
Demand-side behavior is shifting as healthcare systems and patients navigate long-term cardiovascular management. Hypertension and heart failure remain dominant indications for enalapril, supported by its established clinical profile and broad generic availability. Yet the demand narrative is increasingly shaped by adherence considerations, chronic care management programs, and the preference for therapies that integrate smoothly into multiprescriber regimens. In this environment, products that offer reliable supply, consistent bioequivalence performance, and supportive packaging or delivery formats can gain outsized attention from procurement teams and clinical stakeholders who prioritize continuity of care over marginal unit-cost differences.
Cost structure dynamics, particularly around API procurement, add another layer of complexity. Reported pricing disparities across sourcing regions underscore how regulatory compliance requirements, local demand from formulation manufacturers, and regional production costs influence input economics. These variations create opportunities for companies that can secure stable, compliant supply at competitive terms, while also elevating the risk for players dependent on single-source procurement or exposed to currency and logistics volatility.
- Process and formulation innovation can unlock incremental value even after patent expiry, particularly when it addresses adherence or population-specific needs.
- Regulatory approvals for new indications or dosage forms can create temporary differentiation windows and support targeted market access strategies.
- Demand patterns are increasingly influenced by adherence, chronic care integration, and procurement priorities that weigh supply reliability alongside price.
- API cost dispersion across regions encourages diversified sourcing strategies and emphasizes the value of compliant, audit-ready suppliers.
Competitive Landscape and Leading Strategies
The competitive field is defined by a mix of large multinational generic suppliers and specialized API manufacturers concentrated in India, China, Europe, and the United States. This geographic spread reflects both historical manufacturing strengths and the way regulatory pathways shape market entry. Companies with integrated API and formulation capabilities tend to hold an advantage in managing cost, quality, and lead times, while API-focused producers often compete on regulatory filings, export reach, and customization for formulation partners. The presence of multiple suppliers for finished dosage forms indicates a mature competitive environment where scale, regulatory track record, and distribution relationships are central to sustaining share.
Strategic positioning among leading players often hinges on regulatory asset accumulation and market-specific execution. A notable example occurred in mid-2025, when one company expanded its U.S. market footprint by acquiring an FDA-approved abbreviated new drug application for enalapril maleate tablets in multiple strengths from another established manufacturer. Transactions of this type illustrate how regulatory assets can serve as strategic currency, enabling faster commercial entry, portfolio expansion, or geographic rebalancing without the lead time of de novo filings. In parallel, the broader pattern of multiple firms maintaining broad generic tablet portfolios across strengths suggests that competitive advantage increasingly depends on operational reliability, supply continuity, and the ability to serve procurement programs that value predictability.
Epinephrine Market
The market structure appears to be moving through a phase where consolidation and selective diversification coexist. On one hand, acquisition of approved applications and partnerships between API producers and formulators can consolidate capability among players seeking to reduce dependency on external suppliers. On the other hand, specialized entrants continue to find openings in narrower segments, such as alternative formulations or indication-specific supply arrangements. This duality means that incumbents must defend share through cost discipline and quality assurance, while new and expanding participants can pursue differentiated routes tied to regulatory assets, formulation variants, or regional supply agreements.
Several strategic themes recur among stronger performers. First, maintaining a diversified regulatory footprint reduces exposure to single-market pricing pressure and creates options for portfolio optimization. Second, investing in supply chain resilience, including multi-source API strategies and audit-ready quality systems, supports both commercial continuity and customer confidence. Third, building capability around non-tablet formats or specialized indications can create pockets of differentiation in an otherwise crowded field. The interplay of these approaches suggests that long-term success will depend less on molecule novelty and more on execution excellence across regulation, manufacturing, and market access.
- Leading players combine regulatory asset strength with formulation breadth to sustain presence across multiple markets and dosage strengths.
- Acquisition of approved applications and partnership-based supply models are becoming common mechanisms for accelerating market entry and rebalancing portfolios.
- Competitive differentiation is shifting toward supply reliability, quality documentation, and targeted formulation or indication strategies rather than volume alone.
- The coexistence of consolidation activity and niche expansion indicates a market where operational agility and regulatory readiness determine competitive outcomes.
Future Trends and Outlook
Over the next three to five years, the market is likely to be shaped by the interplay of sustained cardiovascular demand, continued generic competition, and incremental regulatory and formulation evolution. One key trend is the ongoing rationalization of supply chains toward greater resilience and documentation rigor. As procurement organizations in major markets place increasing weight on supply continuity and auditable quality, suppliers that can demonstrate robust sourcing, validated processes, and transparent compliance records will be better positioned to secure long-term contracts and withstand price competition. This trend creates commercial opportunities for manufacturers that invest early in supply chain diversification and regulatory readiness, especially where API sourcing is concentrated or vulnerable to external shocks.
A second trend concerns the gradual broadening of usage contexts through formulation and indication refinement. Even in a well-established generic category, approvals that address specific patient populations or delivery preferences can create meaningful commercial differentiation. Products aligned with pediatric, geriatric, or adherence-sensitive use cases may command more favorable positioning in certain procurement and clinical settings, particularly where healthcare providers seek to reduce administration barriers and support long-term therapy continuity. The opportunity here lies not in discovering new therapeutic territory, but in translating existing molecule utility into formats and labeling that better fit practical care delivery.
A third trend is the intensification of pricing discipline as more competitors compete in mature generic segments. With a wide field of suppliers, margin preservation will increasingly depend on operational efficiency, mix management, and value-added services such as reliable delivery, batch consistency, and responsive regulatory support. This environment favors organizations that can manage cost structures without sacrificing quality, and that understand the local procurement dynamics of each market they serve. At the same time, uncertainty remains around reimbursement pressure, regulatory enforcement intensity, and the potential for supply disruptions to alter short-term pricing and availability. Companies that treat these variables as manageable risks rather than external surprises will be better prepared to capture share when conditions shift.
Worldwide Enfuvirtide Market
- Supply chain resilience and documented quality will become more commercially relevant as procurement prioritizes continuity and compliance.
- Formulation and indication refinements offer realistic differentiation opportunities that support adherence and specific patient groups.
- Pricing pressure will reward operational efficiency and market-specific execution, while exposing firms that rely on single-channel volume strategies.
- Regulatory, reimbursement, and supply-side uncertainties will require scenario-aware planning rather than static forecasts.
Actionable Insights for Decision-Makers
For manufacturers, the priority is to strengthen the operational foundations that translate into commercial reliability. Diversifying API sourcing, reinforcing quality documentation, and investing in formulation flexibility can reduce exposure to input cost swings and regulatory interruptions while improving the ability to serve differentiated customer needs. Companies should also evaluate regulatory asset strategies, including the potential to acquire or partner around approved applications, as a means to accelerate entry or expand strength coverage in target markets.
PW Consulting
For investors, the market rewards disciplined exposure to participants with credible supply chains, broad regulatory footprints, and the ability to compete on reliability as much as price. Due diligence should focus on sourcing dependencies, approval pipelines for additional indications or formulations, and the extent to which a company’s portfolio mix supports margin stability in a competitive generic environment. Monitoring transaction activity around regulatory assets can also provide early signals about where capability is consolidating.
For procurement and market access teams, the emphasis should be on qualifying suppliers that can deliver consistent supply and auditable quality without sacrificing cost efficiency. Balancing multi-source strategies with long-term partnership structures can help mitigate disruption risk while preserving negotiating leverage. Where possible, aligning product selection with adherence-friendly formats and reliable delivery performance can support both clinical continuity and total cost-of-care objectives.
For stakeholders seeking a deeper view of regional revenue splits, formulation and indication dynamics, concentration metrics, and company-level strategic profiles, a more comprehensive research resource is available to support detailed planning and scenario modeling.
For detailed analysis of this topic, please visit the official page: Worldwide Enalapril Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Is your Aion 2 character stuck because your wallet can't keep up with your gear upgrades? Want to make better use of the Aion 2 Kinah you earn while farming? This guide explains how to turn everyday gameplay, valuable Aion 2 Items, and smart spending into faster progression—and when it may make sense to buy Aion 2 Kinah to save time.
If you need extra Kinah for an important upgrade, MMOEXP gives players another option to quickly supplement their in-game currency.
Build Your Aion 2 Kinah the Smart Way
A strong Kinah balance gives you more freedom. Instead of constantly worrying about your next upgrade, you can focus on improving your equipment, crafting useful resources, and preparing for tougher content.
The easiest way to build wealth is to combine several income sources rather than relying on one farming method.
Complete daily activities, clear profitable PvE content, gather resources, and sell unwanted loot. Over time, these small sources can add up to a significant amount of Aion 2 Kinah.
Best for: Players who want steady income without turning every gaming session into a boring farming marathon.
Turn Aion 2 Items Into Profit
Your inventory can be much more valuable than it looks.
Don't immediately sell every piece of equipment or material you don't need. Some Aion 2 Items may have strong demand from other players, especially useful crafting materials and desirable equipment.
Before selling anything, check:
Is it useful for my next upgrade?
Can it be traded or sold?
Is its market value higher than the NPC price?
Learning which items are worth keeping can dramatically improve your overall Kinah income.
Farm for Value, Not Just Drops
Efficient farming isn't about killing the most enemies. It's about making the most value from the time you spend playing.
Choose activities that combine Aion 2 Kinah, EXP, equipment, and useful materials. If one farming location gives slightly more currency but takes twice as long, it may actually be less profitable.
Try tracking your earnings over 30–60 minutes. This gives you a much clearer idea of which activities deserve your time.
How to Buy Aion 2 Kinah From MMOEXP
Sometimes you simply don't have enough time to farm everything yourself. If you want to remove a currency bottleneck, you can choose to buy Aion 2 Kinah through MMOEXP.
The process is straightforward:
- Find the Aion 2 Kinah section: Visit MMOEXP and select the appropriate currency category.
- Choose your server: Make sure the listing matches your character's server and faction.
- Pick your quantity: Select an amount that fits your current progression needs.
- Enter your details: Carefully provide the required character information.
- Complete your order: Check the details and follow the listed delivery instructions.
Always review the game's current policies regarding third-party currency purchases before completing a transaction.
How to Find Cheap Aion 2 Kinah
Looking for cheap Aion 2 Kinah can help you control your spending, but the lowest price shouldn't be your only consideration.
Compare the price, quantity, server, and delivery conditions before making a decision. Purchasing exactly what you need for a specific upgrade is often smarter than buying a huge amount simply because the unit price looks attractive.
Final Takeaway
For dedicated farmers, efficient routes can provide a steady source of Aion 2 Kinah. For casual players, selling valuable Aion 2 Items can reduce the amount of time spent grinding. And when you need to overcome a major currency shortage, choosing to buy Aion 2 Kinah can provide a convenient way to support your progression.
Whether you're searching for cheap Aion 2 Kinah or simply want to spend less time farming, MMOEXP can be a convenient option to consider when you're ready to push your character to the next level.
Super High Count Cashmere Yarn Market: Why 5.86% CAGR Reshapes Luxury Growth
By pmarketresearch, 2026-09-18
Strategic Trends and Commercial Opportunities in the Global Super High Count Cashmere Yarn Market
Market Landscape and Core Challenges
The worldwide super high count cashmere yarn market has demonstrated consistent upward momentum over the past five years, with total revenue expanding from approximately $382 million in 2020 to $512 million in 2025. Over the 2026-2032 forecast period, the market is projected to reach $763 million, reflecting a compound annual growth rate of 5.86 percent. This trajectory underscores steady demand for ultra-fine, high-count yarns that deliver exceptional softness, drape, and luxury aesthetics. Revenue growth has been particularly pronounced as brands elevate premium product lines and consumers increasingly prioritize tactile quality and material provenance over volume-driven fashion cycles.
Despite this expansion, the industry faces structural inflection points that will shape competitive outcomes over the next several years. First, raw material volatility continues to complicate planning and margin management. Cashmere fiber prices softened but remained highly unpredictable through late 2025, driven by constrained grazing conditions, shifting buyer sentiment, and evolving trade policies in key sourcing regions. Concurrently, wool and cashmere yarn prices climbed 10 to 15 percent since late 2025 as producers absorbed higher production costs, climate-related pasture stress, and breeding constraints. These cost pressures test the pricing power of downstream manufacturers who must balance premium positioning with consumer willingness to pay.
Second, the regulatory and trade environment is actively reshaping sourcing strategies and value capture. Policy interventions aimed at encouraging domestic processing have altered traditional export patterns, while sustainability certification frameworks are gaining traction across major producing regions. These developments reward vertically integrated players and penalize suppliers reliant on fragmented, opaque supply chains.
Third, the market's moderate concentration means competitive advantage increasingly depends on technical differentiation rather than scale alone. With a relatively small number of established mills controlling meaningful market share, new entrants and existing manufacturers alike must navigate the tension between volume growth and the meticulous fiber selection, dehairing precision, and count consistency required for the highest-tier yarns. The result is a market where premium positioning, traceability, and processing capability will separate long-term winners from commoditized participants.
Key Drivers of Market Transformation
Technological Innovation and Fiber Processing Breakthroughs
Advancements in dehairing technology, fiber grading, and high-count spinning have fundamentally expanded the feasibility of ultra-fine cashmere yarns while improving consistency across large production runs. Modern ring and air-jet spinning systems, combined with refined worsted and semi-worsted processes, enable manufacturers to achieve finer deniers and higher uniformity with reduced pilling and enhanced color stability. These technical gains are particularly important for applications that demand lightweight, drape-forward constructions, where even minor fiber irregularities can compromise end-product performance.
Leading players are leveraging these capabilities to shift from generic premium positioning toward highly specific yarn architectures tailored to luxury apparel and high-end accessories. Firms that integrate fiber selection, dehairing, and spinning under one operational umbrella can control critical quality parameters, reducing variability and enabling repeatable performance at counts that once required painstaking manual intervention. This vertical integration also supports faster iteration cycles for seasonal collections and custom specifications, a growing expectation among luxury brand partners.
Policy and Regulatory Environment
Policy developments are increasingly steering raw material flows toward domestic processing and higher value addition. In mid-2025, Mongolia implemented a ban on exporting uncombed cashmere, a move designed to encourage local refining and capture more margin within the country of origin. This policy shift has reoriented trade patterns and prompted downstream buyers to reassess sourcing pathways, particularly for combed fiber used in high-count yarn production. At the same time, Mongolia's export milestone in 2025—reaching 4,000 tons of combed cashmere valued at $330.6 million, a 28.7 percent increase in value—demonstrates how targeted investments and processing incentives can accelerate value capture. Government commitments to expand processing capacity through substantial investment programs signal a longer-term structural change in how raw material value is distributed across the supply chain.
Parallel to trade policy, sustainability certification frameworks are becoming operational realities rather than aspirational markers. Standards addressing animal welfare, pasture management, and fiber quality are increasingly referenced by brands and retailers seeking to validate responsible sourcing claims. Certification programs that establish model farms and transparent practices in major producing regions are helping to stabilize supply relationships and reduce perceived risk for buyers. Over time, compliance with recognized standards will likely function as a baseline requirement rather than a differentiator, with early adopters benefiting from stronger brand partnerships and preferential access to premium fiber allocations.
Demand-Side Shifts in Consumer and Brand Behavior
Demand for super high count cashmere yarns is being propelled by a consumer base that increasingly associates fiber fineness and craftsmanship with enduring value. Luxury apparel remains the dominant application category, reflecting brand strategies that use ultra-fine yarn constructions to differentiate core collections and justify premium pricing. Beyond apparel, high-end accessories continue to grow as consumers seek tactile quality in smaller, higher-margin items that showcase material excellence without the footprint of full garments.
Brand behavior is also shifting toward responsible sourcing narratives that connect fiber origin to finished product. Traceability, provenance, and sustainability credentials are no longer secondary considerations; they influence design decisions, sourcing contracts, and consumer communication. This trend is particularly pronounced among heritage European houses and forward-looking contemporary brands alike, both of which are seeking yarns that deliver consistent quality while supporting verifiable sustainability claims. The result is a more discerning buyer base that values both performance and transparency, raising the bar for yarn suppliers across the value chain.
Supply Chain and Cost Structure Dynamics
Cost structures are being reshaped by the intersection of raw material constraints, processing incentives, and labor and energy considerations across producing regions. Soft but volatile fiber pricing creates planning complexity, while the 10 to 15 percent increase in yarn prices since late 2025 highlights the need for careful cost-pass-through strategies. Manufacturers that can secure stable fiber access through long-term relationships, vertically integrated operations, or certified sourcing models are better positioned to manage margin compression and maintain consistent output.
At the same time, the promotion of domestic processing in key sourcing countries is altering the economics of import dependency. Buyers who previously relied on imported semi-processed materials now face a landscape where refined combed fiber and finished yarns are increasingly available closer to origin, often accompanied by local investment in spinning capacity and technical know-how. This evolution offers new sourcing flexibility but also demands greater supplier assessment rigor, particularly as regional capacity expands and new entrants compete for premium fiber allocations.
Competitive Landscape and Leading Strategies
The market features a blend of heritage European mills, vertically integrated Chinese producers, and specialized suppliers whose strategies reflect distinct approaches to premium positioning. Italian and Scottish firms continue to leverage reputation, technical heritage, and tight integration with luxury brand relationships to command premium pricing for ultra-fine counts. These players emphasize fiber selection, count consistency, and aesthetic performance, often focusing on specific counts and constructions that align with luxury knitwear and apparel specifications. Their differentiation rests on proven quality, low-pilling performance, consistent coloration, and the ability to support bespoke development cycles for high-value collections.
Chinese producers have scaled capacity and technical capability to serve both domestic and international premium markets. Large-scale manufacturers with multi-thousand-ton annual capacity now offer pure cashmere, blends, recycled, and antibacterial yarns using advanced spinning techniques derived from European best practices. Their strategic advantage lies in scale, customization flexibility, and the ability to produce high-count worsted, woolen, and semi-worsted yarns across a broad specification range. By combining advanced spinning infrastructure with access to Inner Mongolian fibers, these producers can respond to diverse brand requirements while maintaining competitive cost structures.
Vertical integration remains a recurring theme among top performers. Major producers in Inner Mongolia combine fiber sourcing, dehairing, and spinning within integrated operations, enabling tighter control over fiber quality and count consistency. Some mills focus on dehaired cashmere yarns with dedicated capacity for both ring and air-jet spinning, supporting pure and blended offerings across multiple end markets. This integration helps manage volatility in raw material supply and provides a dependable foundation for sustained premium output.
The competitive dynamics are evolving along several axes. Consolidation is likely to continue as larger players acquire technical capabilities, fiber access, or downstream relationships to strengthen premium positioning. Simultaneously, fragmentation persists in niche segments where ultra-fine counts, limited-edition constructions, and sustainability credentials create space for specialized mills that serve a small number of high-value brand partners. New entrants are appearing where investment in processing capacity intersects with regional policy support, particularly in markets investing heavily in domestic refining and spinning infrastructure. Success in this environment requires clear strategic differentiation: either scale-enabled cost efficiency with consistent premium quality, or heritage-driven technical excellence with strong traceability and brand relationships.
Future Trends and Commercial Opportunities
Over the next three to five years, three interconnected trends will shape strategic opportunities in the super high count cashmere yarn market.
-
Sustainability and traceability become procurement prerequisites. Certification frameworks and brand-level sourcing policies will increasingly require documented fiber origin, animal welfare practices, and pasture management standards. Suppliers that can provide verifiable traceability and align with recognized standards will secure preferred access to premium buyers, while laggards face growing exclusion risk from luxury brand procurement processes.
-
Regional processing capacity reshapes sourcing geography. Continued investment in domestic refining and spinning near major fiber origins will expand the availability of high-quality combed fiber and finished yarns closer to source. This creates opportunities for buyers seeking diversified, resilient supply bases and for producers positioned to serve both local premium markets and international brand partners. However, it also raises the importance of supplier qualification, quality assurance, and long-term relationship management as new capacity enters the market.
-
Ultra-fine yarn architectures expand into adjacent premium categories. Advances in spinning consistency and fiber preparation will enable high-count yarns to penetrate new applications beyond luxury apparel and accessories, including lightweight technical knitwear and premium home textiles where softness, drape, and durability matter. Manufacturers that can tailor count, twist, and blend structures to specific end-use requirements will capture value in these expanding niches.
Fashion Luxury Cashmere Clothing Market
These trends carry inherent uncertainty. Raw material price volatility may persist if climate pressures, breeding constraints, and trade policy shifts continue to affect fiber supply. Rapid capacity expansion in processing centers could intensify competition for premium fiber allocations, compressing margins for suppliers unable to differentiate on quality or traceability. Additionally, brand consolidation and shifting consumer preferences toward resale, longevity, or alternative sustainable materials could alter demand intensity for premium yarns. Navigating these risks will require disciplined supplier selection, transparent sourcing narratives, and the ability to adapt product specifications as brand requirements evolve.
Fleece Knitting Yarn Market
Actionable Guidance for Decision Makers
For manufacturers and yarn producers: Prioritize technical differentiation and traceability as core strategic assets. Invest in dehairing precision, count consistency, and color stability to defend premium pricing, and build documented sustainability credentials that align with emerging brand requirements. Evaluate vertical integration opportunities or long-term fiber supply agreements that reduce exposure to raw material volatility and secure access to high-grade fibers. Where capacity expansion is underway, focus on quality assurance and application-specific yarn architectures rather than undifferentiated volume growth.
For investors and corporate strategy teams: Look for value creation in processing capacity supported by policy tailwinds and in suppliers with demonstrable traceability and quality control capabilities. The most resilient opportunities will combine stable fiber access with technical competence in high-count spinning and the ability to serve luxury brand specifications. Assess regional dynamics carefully, particularly where domestic processing incentives are reshaping value capture, and weigh the trade-offs between scale advantages and the premium pricing power that comes from differentiated quality and brand relationships.
For procurement and sourcing leaders: Diversify supply bases to balance quality, resilience, and cost, and embed sustainability and traceability criteria into supplier evaluation from the outset. Establish long-term relationships with mills capable of consistent ultra-fine output and clear documentation of fiber origin and processing practices. As regulations and brand expectations tighten, proactive supplier qualification and transparent sourcing will reduce disruption risk and strengthen brand credibility.
PW Consulting
Detailed segmentation data, regional volume and value breakdowns, and company-level profiles can clarify where to prioritize investment, sourcing, and product development. A comprehensive market assessment provides the granular context needed to evaluate capacity expansions, supplier suitability, and segment-level growth potential with greater precision.
For detailed analysis of this topic, please visit the official page: Worldwide Super High Count Cashmere Yarn Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Industrial Burden Carrier Market 2026: Why 4.95% CAGR Signals a $751M Shift
By pmarketresearch, 2026-09-18
Navigating the Worldwide Industrial Burden Carrier Market: Strategic Trends and Commercial Opportunities (2026–2032)
The global industrial burden carrier market has entered a decisive growth phase, defined by a structural shift from internal combustion to electric propulsion and by widening application scope across manufacturing, logistics, aviation, and healthcare environments. Market valuation climbed from approximately $420.5 million in 2020 to an estimated $535.4 million in 2025, and forward projections indicate sustained expansion toward $750.85 million by 2032.
This trajectory reflects a compound annual growth rate of roughly 4.95 percent across the forecast horizon, with revenue tracked in USD million. The expansion is not merely cyclical; it represents a fundamental recalibration of how facilities move materials, personnel, and equipment within constrained operational footprints. Burden carriers have evolved from niche utility vehicles into integral nodes of intra-facility logistics, bridging gaps between fixed infrastructure and mobile material handling.
Several interconnected challenges and inflection points are reshaping how organizations evaluate burden carrier investments and deployment strategies. First, the industry is navigating a cost and compliance paradox. Zero-emission mandates and indoor air-quality regulations across more than sixty countries are accelerating electrification, yet transition timelines vary significantly by jurisdiction, creating fragmented compliance landscapes and uneven capital planning cycles. Second, supply chain volatility in critical inputs continues to pressure pricing and lead times. Global iron ore benchmarks for China-imported 62% Fe fines are forecast to ease from approximately $100 per ton in 2025 to $90 per ton in 2026, influencing steel costs for chassis and frames. At the same time, US Midwest hot-rolled coil steel prices are expected to trade in the $980 to $1,060 per short ton range in early 2026, with flat to slightly rising trends shaped by tariff dynamics and manufacturing activity. These inputs directly affect build economics for heavy-duty frames, load beds, and structural components. Third, organizations face an operational integration challenge. Rising warehouse automation and persistent labor shortages in manufacturing and logistics sectors are increasing reliance on burden carriers to improve throughput and reduce manual handling, but integrating these vehicles into existing material flow architectures, charging infrastructure, and safety protocols requires disciplined change management.
The market’s concentration profile underscores both stability and opportunity. A core group of established manufacturers holds meaningful share, yet the growth trajectory leaves room for differentiated entrants that can address specialized payloads, ergonomics, and sector-specific compliance requirements.
Hand Trucks Market
Key Drivers Reshaping the Market
Electrification and Propulsion Technology Breakthroughs
Electrification stands as the most conspicuous accelerator in the market. Electric propulsion now commands the overwhelming majority of revenue, reflecting sustained advantages in total cost of ownership, indoor air quality, noise reduction, and simplified maintenance relative to internal combustion alternatives. The performance envelope of electric burden carriers is expanding, with manufacturers introducing flatbed designs, higher payload capacities, enhanced towing capabilities, and cabin configurations that support multi-operator use. Practical demonstrations at industry trade events highlight this shift. At the ARA Show, a new lithium-ion burden carrier featuring a four-seater option and an enclosed cabin option was exhibited, signaling growing demand for versatile, multi-purpose transport platforms. In parallel, enhanced warehouse-focused models are reaching availability, including electric burden carriers with carrying capacities in the 4,400 to 6,600 lb range and towing capacities up to 8,800 lb, tailored for tight pathways and high-throughput environments. These capabilities reduce the need for multiple specialized vehicles, enabling facilities to consolidate intra-facility transport around fewer, more adaptable assets.
Policy and Regulatory Momentum
Regulatory direction continues to reinforce electrification while raising the bar for safety and operational reliability. Zero-emission mandates and indoor air-quality regulations across more than sixty countries, including frameworks aligned with the EU Green Deal and US EPA guidelines, are steering procurement toward electric platforms and away from combustion-based alternatives. Concurrently, ISO 3691-1 safety requirements and verification for self-propelled industrial trucks remain the active standard governing design and operation of related equipment, reinforcing expectations around stability, operator protection, braking, and load handling. For manufacturers and buyers alike, these standards create a predictable compliance baseline but also demand rigorous validation, especially as vehicle designs diversify and operational contexts broaden. Organizations that align product development and procurement with these expectations can reduce time-to-deployment and lower lifecycle risk.
Demand-Side Shifts in Operational Behavior
Demand is being reshaped by changing facility economics and workforce dynamics. Warehouses, distribution centers, manufacturing plants, airports, and healthcare campuses increasingly require flexible, low-emission vehicles that can move both materials and personnel within constrained spaces. The rise of automation and persistent labor constraints heightens the value of burden carriers that improve throughput, reduce manual handling, and integrate cleanly with broader logistics systems. Operator experience is also receiving greater attention. Recent product introductions feature larger operator compartments and improved ergonomics designed specifically for burden carrier applications, reflecting a focus on comfort, visibility, and productivity during extended shifts. As facilities pursue tighter material flow and fewer process handoffs, they are gravitating toward platforms that combine payload flexibility with towing capacity and maneuverability, rather than single-purpose equipment.
Cost Structure and Supply Chain Realities
Cost dynamics are evolving as electrification reduces fuel and maintenance burdens while steel and component inputs continue to fluctuate. Declining iron ore benchmarks may ease some chassis and frame costs, but regional steel pricing remains sensitive to tariffs and manufacturing conditions, keeping build economics in flux. Manufacturers are responding with modular architectures, configurable payloads, and design choices that balance durability with cost efficiency. For buyers, the economic case increasingly centers on total cost of ownership, uptime, and integration rather than sticker price alone. This shifts the purchasing conversation toward lifecycle analysis, charging strategy, parts availability, and service support—factors that can determine whether an initial purchase translates into sustained operational value.
Competitive Landscape and Leading Strategies
The competitive field is anchored by a mix of specialized manufacturers and broader material handling brands, each pursuing distinct value propositions. Motrec International Inc., based in Quebec, Canada, offers customizable electric flatbed burden carriers with load capacities up to 5,000 lbs, targeting heavy-duty material transport in industrial facilities, warehouses, and manufacturing plants. Taylor-Dunn Manufacturing Company, headquartered in Anaheim, California, specializes in electric burden carriers including Bigfoot series models with payloads up to 3,000 lbs and towing up to 10,000+ lbs, suited for warehouses, railyards, airports, and tight industrial pathways. Cushman, part of Textron Specialized Vehicles and based in Augusta, Georgia, provides electric burden carriers such as Titan HD, Minute Miser, and Stock Chaser models for personnel and material transport across warehouses, manufacturing, and commercial industrial settings. Pack Mule, operating under Capacity Trucks in the USA, manufactures heavy-duty NXG and ALPHA series electric burden carriers with high payload and towing capacities for manufacturing plants, warehouses, and distribution centers. Johnson Industries Inc., located in Kentucky, focuses on high-quality industrial burden carrier vehicles emphasizing operator safety and efficiency for mining and heavy industrial applications. Trowin Industries, based in the USA, offers flatbed burden carriers for maintenance, rescue, baggage handling, and passenger transport in industrial environments. Columbia ParCar Corp, in Reedsburg, Wisconsin, supplies Payloader Pro and other electric burden carriers for industrial material and personnel movement. Bobcat Company, headquartered in West Fargo, North Dakota, produces BBC23S-7 and BBC28S-7 electric burden carriers with carrying capacities of 4,400 to 6,600 lbs and towing up to 8,800 lbs for warehouse and construction facilities. Toyota Material Handling, in Columbus, Indiana, includes industrial burden carriers within its broader material handling portfolio for efficient intra-facility transport. HC Forklift America, based in the USA, introduces lithium-ion electric burden carriers with multi-seater options for material, equipment, and personnel transport in manufacturing, airports, and workshops.
Leading strategies reveal clear differentiation paths. One approach centers on customization and payload flexibility, enabling buyers to match vehicle configurations to specific aisle widths, load types, and towing requirements. Another emphasizes ergonomics and multi-purpose use, with larger operator compartments, enclosed cabin options, and multi-seater configurations that support mixed material and personnel transport. A third strategy leans into application specialization, with designs tuned for mining, heavy industrial environments, baggage handling, and rescue operations, where durability, safety, and operational resilience take precedence. Recent developments illustrate this competitive dynamism. Taylor-Dunn launched the Bigfoot S series with a larger operator compartment and improved ergonomics for burden carrier applications, reinforcing the ergonomic and comfort angle. Bobcat Company made the 2026 BBC28S-7 electric burden carrier available with enhanced warehouse capabilities, highlighting the ongoing push to adapt electric platforms for high-throughput logistics. HC Forklift America showcased a new lithium-ion burden carrier with a four-seater option and enclosed cabin option at the ARA Show, reflecting growing interest in versatile, enclosed, multi-operator platforms.
Market evolution appears to be moving along two parallel tracks. On one hand, established brands are extending their electric portfolios and integrating burden carriers into broader material handling ecosystems, creating one-stop sourcing advantages and cross-selling opportunities. On the other hand, specialization is intensifying as buyers seek vehicles optimized for specific workflows, payload profiles, and regulatory environments. This combination suggests a landscape that will continue to support both consolidation among broad-line providers and fragmentation around niche applications, with new entrants competing on configurability, safety features, and total cost of ownership rather than price alone.
Industrial UPS Market
Future Trends and Commercial Implications (2026–2032)
Looking ahead, three trends are likely to shape the next three to five years. First, electrification will deepen into a broader operational standard rather than a procurement preference. As zero-emission mandates and indoor air-quality regulations expand across more jurisdictions, and as lithium-ion technologies improve energy density and charging convenience, facilities will increasingly default to electric burden carriers for both material and personnel transport. This creates opportunity for providers that can deliver reliable charging integration, predictable uptime, and scalable fleet management.
Second, application convergence will accelerate. Vehicles that combine flatbed utility, higher towing capacity, multi-operator seating, and enclosed cabin options will become more valuable as facilities consolidate workflows and reduce the number of specialized assets. The commercial opportunity lies in designing platforms that can serve multiple roles without sacrificing safety, maneuverability, or payload integrity. Buyers will reward flexibility that lowers fleet complexity while maintaining operational resilience.
Third, cost and supply chain management will remain decisive. Even as iron ore price trajectories may ease some steel-related pressures, regional steel pricing, tariff effects, and component availability will continue to influence build economics and delivery timelines. Manufacturers that can stabilize input costs through modular design, strategic sourcing, and configurable options will gain an edge. For buyers, disciplined total cost of ownership analysis, charging infrastructure planning, and service network access will be essential to capturing value.
PW Consulting
Potential risks and uncertainties should not be overlooked. Regulatory timelines and enforcement intensity may diverge by region, creating uneven adoption curves. Supply chain disruptions could affect steel and component availability, influencing pricing and lead times. Safety and compliance expectations, anchored by standards such as ISO 3691-1, will continue to evolve, requiring ongoing validation and design discipline. Organizations that prepare for these dynamics—by diversifying sourcing, aligning procurement with regulatory trajectories, and investing in operator training and infrastructure—will be better positioned to navigate volatility and capitalize on growth.
Strategic Recommendations for Decision Makers
For manufacturers, the priority is to sharpen differentiation around payload flexibility, ergonomics, and application-specific safety while maintaining disciplined cost control. Modular architectures, configurable cabin and flatbed options, and clear compliance alignment can broaden addressable use cases without inflating complexity. Investing in charging compatibility, serviceability, and operator-centered design will strengthen long-term competitiveness as electrification becomes the default.
For investors, the growth profile suggests selective exposure to platforms that combine electric propulsion with multi-purpose capability and strong total cost of ownership narratives. Due diligence should focus on supply chain resilience, regulatory alignment, and the ability to serve high-growth application segments such as logistics, warehousing, and multi-role facility transport. Monitoring regional steel pricing, tariff dynamics, and component availability will help anticipate margin pressures and timing risks.
For procurement and operations leaders, the emphasis should shift from unit price to lifecycle value. Evaluating charging infrastructure needs, uptime expectations, maintenance models, and operator safety features will lead to more durable purchasing decisions. Aligning burden carrier selection with facility workflow, aisle constraints, and future expansion plans can reduce fleet complexity and improve throughput over time.
For organizations seeking deeper segmentation data, company-level benchmarking, and tailored guidance on deployment scenarios, a comprehensive research report is available to support detailed evaluation and planning.
For detailed analysis of this topic, please visit the official page: Worldwide Industrial Burden Carrier Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Absorption Heat Pumps Market: Why Waste Heat Recovery Drives 5.62% CAGR
By pmarketresearch, 2026-09-18
The Worldwide Absorption Heat Pumps Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview and Core Challenges
The global absorption heat pump market has demonstrated steady expansion over the past half-decade, moving from approximately 1.48 billion USD in 2020 to roughly 1.94 billion USD in 2025. The trajectory reflects a compound annual growth rate of about 5.6 percent through the 2026–2032 forecast horizon, with revenues projected to approach 2.85 billion USD by the end of the period. This growth is not uniform across time or geography; the market experienced a brief contraction in 2022 alongside broader industrial supply chain disruptions, followed by a rebound that accelerated into 2024 and 2025 as energy costs and decarbonization mandates reshaped procurement priorities. By 2032, the market is expected to cross the 2.8 billion USD threshold, signaling a structural shift rather than a cyclical upturn. The concentration of revenue among the top three players sits near 48 percent, while the top five collectively account for just over 62 percent, indicating a moderately consolidated landscape with room for specialized entrants and regional champions.
Despite the positive trajectory, the industry faces structural friction that will define competitive outcomes over the next several years. The first challenge is the uneven maturity of working fluid architectures. Water-lithium bromide systems dominate installed capacity because of their reliability and commercial availability, yet ammonia-water configurations offer distinct thermodynamic advantages for certain industrial and large-scale applications. The cost, handling requirements, and regulatory perception of these fluids create a bifurcated market where manufacturers must choose between standardization and performance differentiation. This split complicates scaling, because a platform optimized for one chemistry rarely translates seamlessly to the other without reworked components, certification, or service networks.
A second challenge is the dependency on heat source availability and infrastructure readiness. Absorption heat pumps are thermally driven, which means their economics hinge on access to waste heat, gas-fired inputs, solar thermal, or geothermal energy in forms that are predictable and cost-effective. Facilities with abundant industrial waste heat see rapid payback, but sites without such access must rely on fuel-based or solar-driven configurations, which introduce different cost profiles and operational assumptions. The mismatch between equipment capability and site conditions can stall projects even when efficiency targets are ambitious, turning what appears to be a straightforward retrofit into a feasibility exercise.
The third challenge is regulatory and incentive fragmentation. Energy efficiency programs, building codes, and tax provisions increasingly favor high-efficiency thermally driven systems and waste heat recovery, but the specifics vary by jurisdiction, project type, and compliance timeline. In some regions, updated HVAC efficiency requirements are reshaping which systems can be specified in new construction or major renovations, while in others, federal and state incentives create uneven adoption curves. This patchwork raises the cost of market entry and rewards players who can navigate local codes, documentation, and incentive structures with precision. The recent suspension of operations by a North American gas absorption heat pump manufacturer, while it explores strategic alternatives and asset sale options, illustrates how operational scale, partner ecosystems, and regional demand patterns can converge to create inflection points.
Key Drivers Behind Market Momentum
Technology innovation is reshaping the value proposition of absorption heat pumps by pushing efficiency boundaries and widening the range of usable heat sources. Multi-effect and high-efficiency absorption cycles are reducing primary energy consumption in applications where waste heat or gas-fired input is available, allowing operators to convert otherwise lost thermal energy into useful heating or cooling. Advances in heat exchanger design, control logic, and component durability are also improving part-load performance and reducing maintenance intensity, which matters increasingly for commercial and industrial operators who evaluate total cost of ownership rather than first cost alone. As manufacturers accumulate patent portfolios and field data across hundreds of installations, the credibility gap between absorption systems and conventional electric alternatives continues to narrow in niche applications where thermal integration is achievable.
Policy and regulatory momentum is another powerful driver. In markets that are tightening HVAC efficiency requirements or incentivizing decarbonized thermal systems, absorption heat pumps benefit from their ability to leverage waste heat, reduce electrical load, and lower direct emissions in specific configurations. Updated building codes that raise equipment efficiency thresholds can either create compliance pathways for thermally driven systems or raise the bar for integration and controls. Similarly, tax credits and efficiency programs that reward high-performance heat pump adoption provide a financial tailwind for projects that can demonstrate measurable energy savings. The strategic implication is that policy is not merely a background condition; it is becoming a design parameter. Manufacturers and project developers that align product roadmaps with evolving code cycles and incentive eligibility are better positioned to secure specification wins and shorten sales cycles.
Geothermal Heat Pump Market
Demand-side behavior is changing as well. Industrial operators are increasingly treating waste heat recovery as a strategic resource rather than a byproduct, especially where energy intensity and fuel volatility are persistent concerns. Commercial and residential segments are also showing greater interest in thermally driven options where gas availability, grid constraints, or decarbonization goals make electric compression systems less attractive in specific contexts. This demand evolution is shifting procurement discussions from narrow equipment comparisons to system-level outcomes: how much waste heat can be absorbed, how the system interacts with existing infrastructure, and how the operating profile aligns with long-term energy planning. The result is a more consultative buying process that rewards suppliers capable of engineering around site-specific heat sources and load profiles.
Supply chain and cost structure dynamics reinforce these shifts. The availability and pricing of key materials such as lithium bromide influence system economics, particularly for water-lithium bromide platforms that represent the larger share of installed capacity. At the same time, gas-fired and thermally driven configurations can become more attractive when electricity pricing is volatile or when waste heat is abundant enough to offset fuel input. Suppliers that can stabilize component sourcing, localize assembly where incentives favor it, and offer flexible drive configurations gain an advantage in projects where lead times and cost predictability are critical. The broader effect is a market in which cost leadership is increasingly tied to integration capability, material strategy, and the ability to match drive sources to local energy realities.
Competitive Landscape and Leading Strategies
The competitive field combines large global manufacturers with specialized leaders that have built deep expertise in particular working fluids, capacities, or end-use segments. Shuangliang Eco-Energy has established a strong position in industrial lithium bromide absorption heat pumps, accumulating a broad international installation base and a substantial patent portfolio focused on high-efficiency waste heat recovery and significant energy savings. Its strategy emphasizes long-cycle industrial deployments where proven performance and energy reduction claims are central to procurement decisions. Johnson Controls, through its YORK portfolio, offers a wide range of absorption chillers and heat pumps that can be driven by multiple heat sources, targeting commercial and industrial applications where waste heat utilization, water savings, and emissions reduction are priorities. Its long operating history gives it visibility across a broad set of building and facility types, which supports specification relationships and service continuity.
BROAD Group has scaled rapidly as one of the largest manufacturers of absorption chillers and heat pumps, with a product range that spans smaller commercial units to large industrial capacities and a strong focus on gas-fired and thermally driven systems. Its extensive global deployment base reflects an aggressive push into commercial, civil, and industrial markets, supported by volume manufacturing and a broad application footprint. Thermax Limited has carved out a position around advanced absorption chillers and triple-effect technology, emphasizing high-efficiency, multi-energy-driven systems for industrial use and exporting its capabilities across global markets. Robur S.p.A. distinguishes itself through gas absorption and ammonia-based heat pump and chiller solutions, with models designed to deliver high effective efficiency and a reduced carbon footprint in commercial and residential settings. Hope Deepblue, Ebara, and Berg Chilling Systems, including its partnership with World Energy, round out a field that spans lithium bromide systems, waste heat recovery pumps, and marine or exhaust-gas-driven configurations, each targeting specific performance, durability, or application requirements.
The strategic differentiation among these players is becoming clearer. Some compete primarily on proven industrial scale, patent depth, and waste heat recovery performance; others compete on portfolio breadth, multi-source drive capability, and brand recognition across commercial buildings; still others compete on specialized chemistries such as ammonia or on niche application engineering such as marine and offshore environments. The most resilient players are those that can translate technical differentiation into measurable operating outcomes and then support those claims with service, documentation, and local compliance knowledge. Price competition exists, but in many project categories the decisive factors are integration risk, heat source compatibility, and the ability to satisfy efficiency and code requirements without excessive customization.
The market structure is evolving along two converging paths. On one hand, consolidation pressure is rising among suppliers that need broader geographic coverage, service networks, and application libraries to win larger industrial and infrastructure projects. On the other hand, segmentation is deepening because working fluid choices, heat source types, and end-user requirements reward focused expertise. New entrants or asset-level moves, such as the recent North American situation involving a gas absorption heat pump manufacturer exploring a partner or asset sale, suggest that regional manufacturing footprints and brand continuity can become strategic assets in themselves. The likely outcome is a landscape where a handful of global platforms coexist with specialized leaders and regional capabilities, and where partnerships, distribution agreements, and selective acquisitions become common tools for expanding reach without abandoning technical focus.
Outlook for the Next Three to Five Years
Looking ahead, one defining trend will be the wider use of absorption heat pumps as part of integrated thermal hubs rather than standalone equipment purchases. Industrial facilities and large commercial campuses are increasingly viewed as systems where waste heat, cooling, heating, and sometimes solar or geothermal inputs can be coordinated. In that context, absorption heat pumps that can accept multiple drive sources and operate efficiently across variable loads will be favored, because they fit into broader energy orchestration strategies. The commercial opportunity lies in bundling equipment with feasibility assessment, control integration, and commissioning support, turning a hardware sale into a performance-based engagement with clearer payback certainty.
A second trend is the gradual expansion of ammonia-water and advanced multi-effect architectures in selected industrial and large-scale applications, alongside continued dominance of water-lithium bromide in mainstream commercial and many industrial settings. As operators seek higher effective efficiency or need to handle specific temperature and capacity ranges, the choice of working fluid will become more application-specific. This creates opportunities for suppliers that can offer certified, well-supported ammonia-based solutions where safety and handling requirements are manageable, as well as for manufacturers that continue to improve lithium bromide system efficiency and standardization. The uncertainty is that regulatory interpretation, operator familiarity, and service readiness will influence adoption speed, meaning that technical superiority alone will not guarantee market share without ecosystem support.
PW Consulting
A third trend is the widening but uneven impact of efficiency codes and incentives. As jurisdictions update HVAC requirements and extend fiscal support for high-efficiency heat pump applications, some regions will see faster project pipelines and stronger specification momentum, while others lag. This unevenness favors players who can localize documentation, support code compliance, and align product offerings with the incentive programs that matter locally. The main risk is that policy timing, program eligibility details, and equipment eligibility interpretations can shift, altering project economics after a pipeline has been planned. Companies that treat policy as a variable to monitor rather than a fixed assumption will be better able to sequence investments, adjust offerings, and protect margins.
Recommendations for Decision-Makers
For manufacturers, the strategic priority is to align product roadmaps with the most defensible demand pockets rather than chasing broad coverage. That means clarifying where waste heat recovery, gas-fired thermally driven systems, or solar/geothermal inputs provide a genuine economic edge, and then investing in the working fluid platforms, component supply stability, and application documentation that support those segments. Differentiation should be expressed in operating outcomes and integration ease, supported by service capacity and compliance knowledge that reduce project risk for buyers. Partnerships for regional distribution, asset continuity, or application-specific engineering can be more efficient than attempting to build every capability internally.
Air Source Heat Pumps Market
For investors, the opportunity is strongest where installed base, patent depth, and regional demand alignment converge, especially in industrial lithium bromide platforms, large-scale gas-fired systems, and specialized ammonia or multi-effect offerings that serve high-value niches. Due diligence should focus on heat source dependency risk, incentive exposure, material cost sensitivity, and the resilience of service and distribution networks, because those factors determine whether growth is sustainable through code cycles and energy price swings. Company-level transitions, such as asset reshuffling or relaunch efforts in specific regions, can create both risk and entry points, so valuation should weigh ecosystem continuity as heavily as technical claims.
For procurement and facility leaders, the priority is to evaluate absorption heat pump options on system-level economics rather than equipment-level specifications. Projects should be screened for heat source availability, compatibility with existing infrastructure, control integration needs, and eligibility for relevant efficiency incentives, with attention to the code cycles that affect new construction or major renovation. Where thermal integration is strong, absorption systems can deliver meaningful operational benefits; where heat source conditions are uncertain, the value proposition weakens quickly. In either case, engaging detailed market intelligence and segment-level data before committing to a technology path helps avoid overgeneralization and supports more accurate total cost of ownership comparisons across the options that matter for the project.
For detailed analysis of this topic, please visit the official page: Worldwide Absorption Heat Pumps Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com